Category Archives: Leadership

Unlocking Trapped Value with AI

Unlocking Trapped Value with AI

GUEST POST from Geoffrey Moore

Two topics that have been on my mind a lot lately are generative AI and trapped value, so I am delighted to have them come together in a single blog. Here’s how it plays out.

Releasing trapped value is the engine that fuels ROI from technology deployments. All systems trap value somewhere in their operations, something that is confirmed by the Second Law of Thermodynamics, which means there will never be a time when there is no ROI to be gained. Where it is to be gained from, on the other hand, is up for grabs. The goal of my advisory practice is to help clients target the most impactful sources of trapped value in their target markets and direct their product roadmaps and go-to-market initiatives accordingly.

When I consider the extraordinary potential of generative AI to release trapped value across virtually any set of systems, I think the industry is, at present, overly infatuated with co-piloting and overlooking a far more impactful source of trapped value staring them right in the face. Look, co-piloting is useful, but how much trapped value is there in the delta between unaided and aided performance from white-collar professionals? Some, for sure, but is this really the burning platform that will drive customer spending to a level that might justify the extraordinary valuations generative AI companies are garnering at present? Probably not. So, what could?

My choice would be the market-facing user interface to any and all systems of engagement. This is where enterprises seek to enlist their customers and partners to utilize their systems for purposes of marketing, sales, service, and commerce, and that is precisely what we, as their external constituencies, want to do. But, how well is this working? Well, compared to the twentieth century, when, effectively, we had no systems of engagement, amazingly well. But by twenty-first-century standards, truth be told, they suck.

Where is the trapped value? Two areas jump to mind. The first is passwords, which have gone from being a source of security to a source of breaches, all the while creating massive amounts of aggravation in the process. The second is the user interface itself. No matter how well designed it is, it is inherently unfamiliar to the first-time or even occasional end user. Because of this friction at the point of user interaction, I submit, systems of engagement are delivering far less than their full value-creating potential.

Enter generative AI. The conversational interface that ChatGPT taught us to know and love is familiar to anyone who speaks the same language as the vendor, and the video, sound, and image recognition capabilities, supplemented by information from the idiosyncratic features that every online device entails, are far better equipped to identify and authorize end users than any set of passwords of two-factor authentication. So, the friction-removing technology is already here. What we are lacking is the friction-removing killer app, the one that every enterprise would embrace in a heartbeat were it available to them.

That app is a universal user interface that can be bolted onto APIs from enterprise systems to mediate between the legacy instruction system of the underlying software and the desires and intentions of the occasional end user. This would entail a (Very) Small Language Model to be developed by enterprise application vendors, as well as a companion SLM from cybersecurity system vendors, but really, how hard is that, especially when compared to the ROI rewards?

This is not just a big opportunity. It is an urgent one as well. Governments and NGOs struggle today to finance systems of engagement that allow programs to scale in the social sector, and their adoption is far below what one would wish, in large part because of the layers of friction we continue to impose. Enterprises that are seeking to catch the next wave of disruption roiling their industries are desperate to engage the customer bases, but are falling short because it is just too painful.

It is hard for me to see a more compelling use case for generative AI at this time, and I hope that industry will agree and free us from the Lilliputian bonds that restrict us.

That’s what I think. What do you think?

— Image credit: Unsplash
Subscribe to Human-Centered Change & Innovation WeeklySign up here to join 17,000+ leaders getting Human-Centered Change & Innovation Weekly delivered to their inbox every week.
How to Calculate Employee Experience ROI (+ Free Calculator)

How to Calculate Employee Experience ROI (+ Free Calculator)

by Braden Kelley and Art Inteligencia

Most executive teams already believe that employee experience matters. Ask them in a planning meeting and you’ll get nods all around the table. Then ask the harder question: what is a specific improvement to the employee experience worth, in dollars, next year? The nods stop.

That gap is why so many worthwhile investments in people stall in budget season. A manager development program, a fix for a broken onboarding process, a serious attempt to remove the daily friction that wears people down: each of them competes with projects that arrive with a number attached. If you can’t attach one, the project usually loses to something that can.

This article walks through how to attach one. It’s built on the same approach as my customer experience ROI calculator, applied to the people on the other side of the experience, and it comes with a free tool so you can run your own numbers.

What the research does and doesn’t say

There’s a lot of research connecting employee engagement to business results, and the best-known source is Gallup. In its comparison of top-quartile and bottom-quartile engagement teams, Gallup reports that the most engaged teams show about 23% higher profitability, 14% higher productivity and 78% less absenteeism. Turnover is 51% lower in low-turnover organizations and 21% lower in high-turnover ones.

Gallup also puts the cost of replacing an employee at one-half to two times the person’s annual salary, and reports that 52% of employees who leave voluntarily say their manager or organization could have done something to prevent it.

Those are striking numbers, and I want to be careful with them, because they’re easy to misuse. They compare very different teams, so they show a strong association, not proof that raising your own score by ten points will produce a particular result. They also aren’t per-point rates, so you can’t take “78% less absenteeism” and apply it to a modest improvement. Treat the research as evidence that the connection is real and large enough to be worth modeling, then model it with your own numbers and cautious assumptions.

The value chain: from a score to a dollar

The idea behind the calculator is a four-step chain.

  1. An experience metric. Engagement, eNPS, or a pulse score: whatever you already track.
  2. A behavioral outcome. People who have a better experience at work tend to stay longer, miss less work and contribute more.
  3. A financial outcome. Each of those behaviors has a dollar value: avoided replacement cost, recovered working time, more output from the same payroll.
  4. An intervention. The specific change that moves the metric in the first place.

The fourth step is the one people skip. Plenty of engagement initiatives improve a survey score without changing anyone’s behavior, so they never reach the financial outcome. A credible business case names the intervention, explains how it changes what people actually do, and then estimates what that behavior change is worth.

What the calculator measures

The EX Value Ledger estimates three kinds of value from an improvement in your experience score:

  • Avoided turnover cost. Fewer people leave, so you pay for fewer replacements. This is usually the largest and most defensible line.
  • Recovered absence time. Fewer unplanned absence days means more paid time spent working.
  • Productivity value. More output from the same payroll. It’s the softest of the three, so the calculator shows it separately and leaves it out of the total unless you choose to include it.

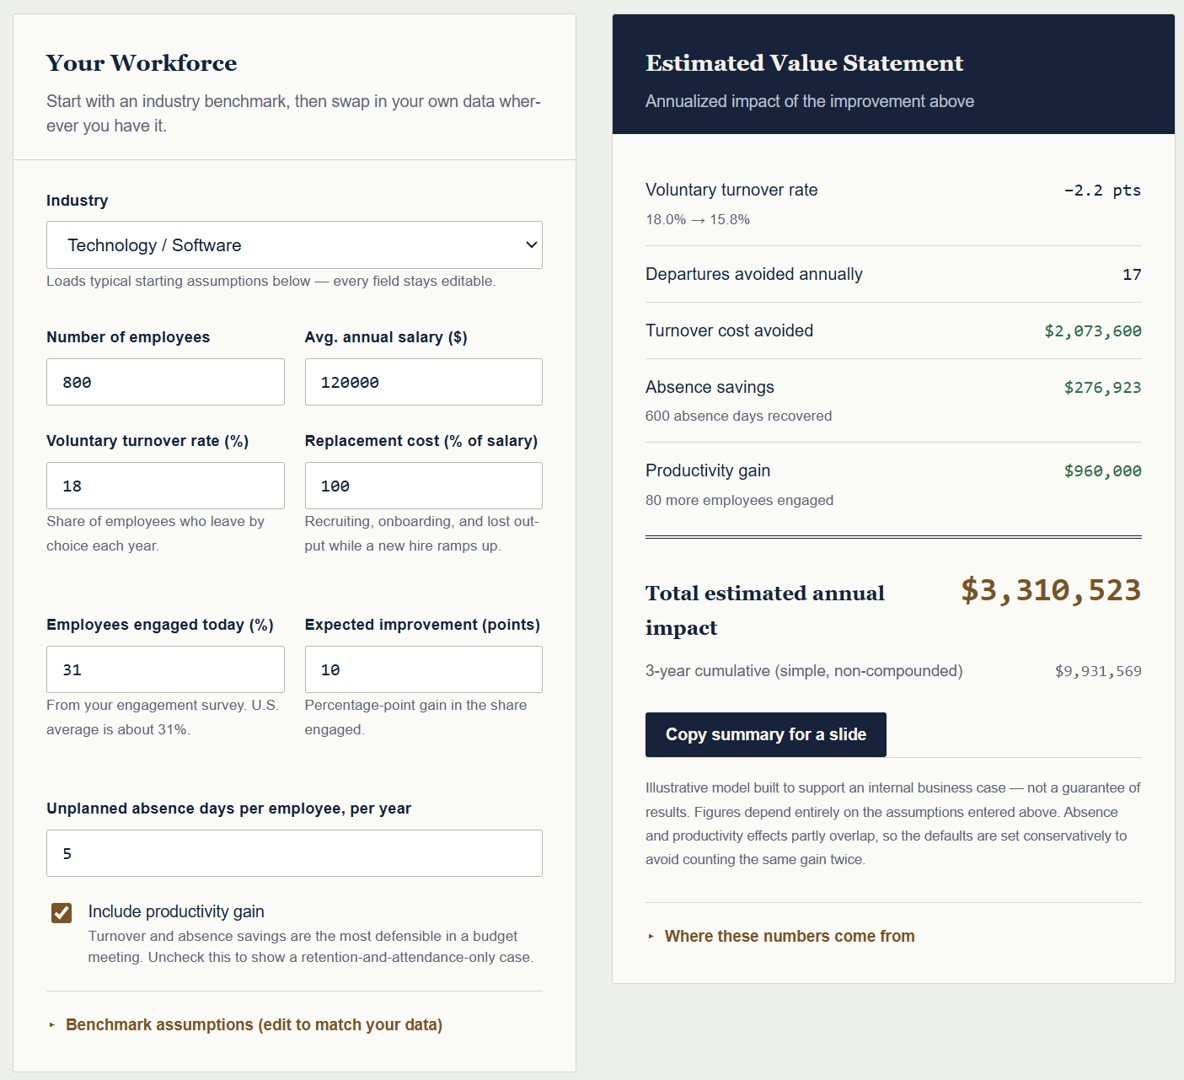
You enter your headcount, average salary, annual turnover rate, replacement cost as a percentage of salary, absence days per employee, your current experience score and the improvement you expect. If you have a program cost, add it and the tool also shows net value and a return multiple.

Starting points when you don’t have your own data

Not everyone has clean turnover figures at their fingertips. The calculator includes three starting profiles you can load and then overwrite. These are illustrative starting points, not industry statistics:

Illustrative turnover profiles used as starting points in the EX ROI calculator
Profile Annual turnover Notes
Lower-turnover environment about 12% Stable workforce, longer tenures
Typical environment about 20% A reasonable midpoint to start from
High-turnover environment about 45% Gallup uses 40% as its line for “high-turnover” organizations

For replacement cost, Gallup’s one-half to two times salary range is wide, and where you land depends on the role and how much knowledge walks out the door with the person. The calculator defaults to 100% of salary, so adjust it to what you know about your own hiring and ramp-up costs.

A worked example

Here’s what the tool produces with its default settings, so you can see how the pieces fit. Suppose a company has 250 employees at an average salary of $75,000, 20% annual turnover and five unplanned absence days per person. It runs a program expected to raise its experience score by ten points.

The calculator’s conservative defaults assume that a ten-point gain cuts turnover by about 5% in relative terms, so a 20% turnover rate drops to 19%. That’s roughly two and a half fewer departures a year. At a replacement cost of 100% of salary, that’s about $187,500 in avoided turnover cost. Add about $18,000 in recovered absence time, and the estimate comes to roughly $205,000 a year, or about $616,000 over three years on a simple, non-compounded basis.

The productivity line adds another estimate on top, shown separately because it’s easier for a skeptic to challenge. That’s the point: you lead with the number you can defend, and present the rest as upside.

This is an illustrative model, not a forecast. Change the inputs to match your organization, and the answer changes with them.

Turning the number into a business case

A number on its own doesn’t win a budget argument. A few habits make the difference.

Use your own figures first. The strongest estimate always starts with your real turnover rate, your real salary data and your real absence numbers. Starting profiles are for getting unstuck, not for presenting to a CFO.

Separate what’s established from what’s estimated. Be clear about which parts come from published research and which come from your own assumptions. A CFO will trust a model more when it shows where the soft spots are.

Model a range. Run a conservative case, an expected case and an optimistic one by changing the sensitivity assumptions. A range signals honesty, and it protects you if results land a bit below the middle.

Tie it to a specific initiative. “Improve employee experience” is not a project. “Redesign onboarding for the first 90 days” is. Attach the estimate to the thing you’d actually do, and say how it changes behavior.

Lead with the defensible lines. Turnover and absence are measurable and familiar to finance. Productivity is plausible but harder to prove. Present them in that order.

Where a score comes from

A calculator can tell you what a better score is worth. It can’t tell you what’s dragging yours down. That requires looking at how work actually gets done: the tools that slow people down, the approvals that add nothing, the handoffs where things fall through, and the frontline knowledge that never makes it up the chain.

That’s what an experience audit is for. It replaces internal assumptions with an accurate picture of what people really experience, and it gives you a prioritized view of where to invest first. Used together, the calculator sizes the opportunity and the audit finds the specific friction behind it.

If you’re also looking at the customer side of the equation, the CX ROI Calculator works the same way for revenue retained and cost to serve, and the two make a useful pair when you’re building the case for a broader experience investment.

Try it

The Employee Experience ROI Calculator is free and requires no signup. Enter your numbers, adjust the assumptions, and use “Copy summary for a slide” to bring the estimate straight into your next budget meeting. If you’d like the full research behind the numbers, the page also offers the EX ROI Benchmark Report by email.

And if you’d like help applying it to your organization’s specific situation, or finding out what’s actually driving your experience score, get in touch for a no-obligation conversation about an Experience Audit.

Sources


Get the EX ROI Benchmark Report — the full industry benchmark table with sources, the EX Value Chain framework, and answers to the five objections a CFO is most likely to raise. Enter your email and we’ll send it straight to your inbox.


Image Credit: Braden Kelley

Content Authenticity Statement: The topic area, key elements to focus on, etc. were decisions made by Braden Kelley, with a little help from Claude to clean up the article.

Subscribe to Human-Centered Change & Innovation WeeklySign up here to get Human-Centered Change & Innovation Weekly delivered to your inbox every week.

What’s the Truth?

What's the Truth?

GUEST POST from Geoffrey Moore

This is the second in a series of responses to the MSN post “20 Philosophical Questions That Are Hard to Wrap Your Head Around.” We are on Question #2: Is there a truth? Here’s the MSN blurb:

This inquiry challenges the concept of truths, versus realities prompting introspection on the nature of knowledge and certainty. Many philosophers consider truth to be a concept that cannot be fully explained in terms other than truth itself. The accepted perspective is that truth relates to how well our language or thoughts align, with a world that exists independently of our minds. This theory is known as the correspondence theory of truth.

There is a fundamental premise stated here that needs correction, namely that “truth relates to how well our language or thoughts align with a world that exists independently of our minds.” The correspondence theory is indeed one understanding of what constitutes truth, but there are two others that are equally well-accepted perspectives—the coherence theory and the pragmatic theory. Thus, while correspondence is indeed a measure of how well our language and thoughts align with a world that exists independently of our minds, coherence, by contrast, is a measure of how well any given claim aligns with all the other claims we take to be true, basically our body of understanding of how the world works. Pragmatism provides a third perspective on truth, taking it to be a measure of how well any claim we make aligns with the results we get from acting out that claim in the world.

All three of these perspectives are useful, and the good news is they are not mutually exclusive. The way we normally test for truth is first through coherence theory. That is, when we hear a claim, we check to see if it aligns with our existing understanding of things. If it does, we are likely to just accept it and move on. If it does not, however, then we are moved to investigate whether it corresponds to what is actually the case, doing so by examining evidence for or against the claim. If the evidence does indeed warrant the claim, then we are moved to modify our body of beliefs to absorb this new bit of understanding into a revised coherence model, what we normally call learning or gaining in experience.

Pragmatism overlays another layer of interest, namely, does this claim enable us to have more success in whatever efforts we have underway? Successful outcomes, in other words, are a form of evidence for the validity of the claim. We have to be careful here, however, for the outcome’s success may be due to some factor other than the one claimed. Nonetheless, when things do work, and especially when this applies to things that traditionally have not worked anywhere near as well in the past, it sends us a strong signal to update our coherence and correspondence models accordingly.

Another challenge that pragmatism poses to our understanding of truth is that lying can also deliver successful outcomes. Lying may often defeat itself in the long run, but in the short run, it can be very effective. How we address lying, however, is normally more of a social issue than a philosophical one. For it to be philosophical, one would need to make the case that lying is foundational to wellbeing, and while such an argument is not unimaginable, it carries with it enough problems that we can safely ignore it for the time being.

What we cannot ignore, on the other hand, is the political use of lying. This is foundational to all authoritarian regimes. In order to stay in power, they must continually maintain a heightened sense of fear and anxiety in the population they govern, at a level sufficient to gain its acquiescence to their corrupt and self-serving ways. How citizens can respond to this challenge is something we will address in a moment.

The core question people want answered about truth, though, is whether or not it is a thing. That is, is truth a force in the world, the way love is or the way beauty is? Historically, the answer to this question was yes because truth, like love and beauty, is taken to be an attribute of the divine being that governs all human experience. In a secular world, however, that answer needs to be revisited. When we do so, we see that the desire for love, beauty, and truth still abides. They do indeed exert a force on us. So, if they are forces in the world, where are they to be found?

My answer is that each one is anchored on a different stair in the Infinite Staircase. Love is grounded on the stairstep of values, an inherent part of our mammalian heritage of nurturing the young. Beauty is grounded on the stairstep of culture, a learned appreciation for esthetic experience. Truth, in this context, is located on the stairstep of narrative, subject to verification delivered from the stairstep of analytics.

Narrative, in other words, is the force in the world that mobilizes the power of truth. True narratives are foundational to both personal and social wellbeing. False narratives undermine these same foundations. Let’s look at examples of both.

The power of true narratives manifests when people act in service to their narrative, even at a cost to their personal self-interests. We call this form of truth integrity, and it is genuinely inspiring because it cements the meaningfulness of their commitments. Existentialism represents an entire philosophy based on this core idea. Its life goal is to be authentic, with authenticity defined as behavior aligned with and in service to whatever life narrative you have chosen for yourself. Truth, in this sense, really does make you free, whereas falsehood imprisons you in narrative contradictions that ultimately destroy your wellbeing, a state that is termed bad faith.

False narratives pose a different problem. The power of truth to combat them depends upon the principled deployment of analytics. Unfortunately, the hold of any narrative on the personality, whether true or false, is frequently stronger than analytics can dislodge. As a result, regardless of how strong the evidence is for falsehood, it is simply denied, allowing bad faith and lack of wellbeing to spread pervasively and sustain their position of power far longer than one might imagine. This is the condition of life under an authoritarian regime.

To dislodge such a regime requires going below the stairstep of competing narratives down to the stairstep of core mammalian values and resurrecting those values that the regime is violating. This is dangerous work, for the regime is well aware of its vulnerability to this tactic and will aggressively punish any signs of it. The prospects for success in the short term are not good, and support from entities outside the regime are likely be necessary to dislodge it, so we should not be surprised to see societies continue to persist under painfully oppressive circumstances.

That said, when the global cannot be addressed, we must retreat and draw in the boundaries to find a local that can be. At the extreme, this would be oneself, although as social creatures, we need the help of a community of others to stay the course, family being our most obvious opportunity. Whatever its nature, that community becomes our reason for being, and it is here that we must use truth to establish the relationships of trust that hold us together. Truth in this context looks more like the medieval troth, a term for fidelity and faithfulness, a kind of integrity that is anchored in our pledge to others to be there for them and with them. Keeping faith is a form of integrity that is well suited to coping with adverse circumstances.

So, is there a truth? Well, in this last sense, there certainly is, as people have proved the world over. As we expand outward from our local scenes, and as we raise the level of abstraction, there will be truth as long as, to borrow a phrase from Yeats, “the center holds.” At some point, it will not, and we must reconcile ourselves to the limits of our mortal perspective, embracing humility and foregoing the kind of righteousness that seeks to impose an answer by force.

That’s what I think. What do you think?

— Image credit: Unsplash

Subscribe to Human-Centered Change & Innovation WeeklySign up here to join 17,000+ leaders getting Human-Centered Change & Innovation Weekly delivered to their inbox every week.
How to Present Strategic Uncertainty to Your Board Without Looking Indecisive

How to Present Strategic Uncertainty to Your Board Without Looking Indecisive

by Braden Kelley and Art Inteligencia

There’s a particular silence that falls over a boardroom when a strategy leader says the words “we’re not certain.”

It lasts about two seconds. In those two seconds, directors are doing math. Is this person hedging? Do they know what they’re doing? Why am I paying for a plan that isn’t sure of itself? By the time the silence breaks, you’ve either lost the room or you’ve earned something rarer than confidence, which is credibility.

Which one you get depends almost entirely on how you present the uncertainty. If you’re a CSO or strategy leader heading into the 2027 planning cycle, here’s how I’d approach it.

Why the instinct to hide uncertainty backfires

The temptation is understandable. Boards want decisions. Executives are rewarded for sounding sure. So the natural move is to smooth over the unknowns and present a single confident number, a single confident forecast and a single confident plan.

The trouble is that directors aren’t naive. Most of them have sat through enough planning cycles to know that a forecast with no stated uncertainty is either a forecast nobody questioned or one somebody hid the doubt inside. When reality drifts from the plan, as it always does, the board doesn’t just see a miss. It sees a team that never told them the miss was possible.

Hidden uncertainty feels safe on the day you present. It’s expensive on the day you’re wrong.

What boards actually worry about

When directors push back on uncertainty, it’s rarely because they dislike uncertainty. It’s because they’re asking three more specific questions:

  1. Does management understand the risks? Not “are there risks,” which everyone knows, but “have you thought about the right ones?”
  2. Is there a plan if things go differently? A board doesn’t need certainty. It needs to know you won’t be paralyzed.
  3. Will we find out in time? The real fear isn’t that the future is unknown. It’s learning about a problem late.

Notice that none of these require you to pretend to know the future. They require you to show you’ve thought about it. That’s a much easier thing to be good at.

The structure that works: firm on action, explicit on uncertainty

The reframe that has served me best is this: be firm about what you’re doing, and be explicit about what you don’t know. These are different things, and mixing them up is what makes uncertainty sound like indecision.

Here’s a structure you can use.

  1. Start with the decision, not the doubt. Lead with what you’re recommending. “We recommend investing in X, Y and Z in 2027.” Boards relax when they hear a position before they hear a caveat.
  2. Name the few uncertainties that actually matter. Not twenty. Three or four. Pick the ones that, if they break differently than expected, would change your strategy. If an uncertainty wouldn’t change a decision, leave it out. It’s noise, and it dilutes the ones that count.
  3. Show the futures, not just the risks. Instead of a list of risks, describe a small set of genuinely different ways the next few years could unfold, each traced back to signals the board can see. It’s more concrete than “risks,” and it lets directors engage with the world you’re describing instead of with an abstract worry.
  4. Separate no-regret moves from bets. Tell the board which parts of the plan hold up in every future you described, and which depend on one future arriving. Directors love this, because it shows you know exactly where the real exposure is.
  5. Show your tripwires. For each major uncertainty, say what you’d have to see to conclude things are going the other way, who is watching for it, and what you’d do. This answers the board’s third question directly. You won’t be the last to know.
  6. Close on how you’ll report back. Tell them when and how they’ll hear about changes. A predictable rhythm of updates turns uncertainty from a source of anxiety into a managed process.

Language that helps, and language that hurts

Small word choices matter more than you’d expect in this setting.

Instead of “we don’t know,” try “here’s what we know, here’s what we’re watching, and here’s what we’d do if it changes.”

Instead of “it depends,” try “it depends on two things, and here’s how we’ll know which way each is going.”

Instead of “we think maybe,” try “our current view, based on these signals, is…” Then give it a rough confidence level. “We’re fairly confident in this one and much less confident in that one” is a perfectly respectable thing to say to a board.

Instead of a single number, give a range and the assumption it rests on. A range with a stated assumption signals competence. A single number with no assumptions signals either naivety or a hidden agenda.

And avoid the two extremes: false precision, which gets punished later, and endless hedging, which gets punished now.

Use a picture

One practical suggestion. Directors take in far more from a single well-built visual than from twenty slides of text. If you can put the signals, the trends and the possible futures onto one shared page, with the most probable future and your preferred path marked, the board can see the whole argument at once and point at the part they’d like to discuss. That’s a much better conversation than one where everyone is holding a slightly different mental picture of what you meant.

That’s the reasoning behind the visual approach in FutureHacking™: it moves a leadership team from signals, through trends, to a set of possible futures and a preferred path, on a page everyone can see. A team that has worked that way arrives at the boardroom with the thinking already organized.

Rehearse the hard question

Before the meeting, find the toughest director and ask yourself what they’d say. Usually it’s some version of “so which is it?” Have a short, clear answer: “Our most likely future is this one, and here’s why. We’ve built the plan so it works if we’re wrong.” If you can say that without flinching, you’ve already won the room.

A way to get started

If your team hasn’t yet pulled together the signals behind your current view of the future, the free FutureHacking Signal Picker helps you identify and prioritize the signals worth watching, which gives you the evidence to point to when the board asks where your view comes from.

I’m also finishing the FutureCanvas Picker, which takes planners through the whole arc, from signals to trends to possible futures to your most probable future and the path toward the one you’d prefer. I’m opening early access to a select group first: CSOs, strategic planners and leaders preparing for planning cycles and board conversations right now, who can tell me honestly what works under real deadline pressure. If that’s you, reach out and let me know and I’ll follow up personally with the select few who get in first.

The credibility dividend

Here’s the long game. The leaders who present uncertainty well don’t just survive the meeting. They build a reputation for telling the board the truth early, and that reputation is worth more than any single forecast. The next time something goes sideways, the board remembers who warned them and who didn’t.

Present the uncertainty. Just make sure the plan looks like it was built by someone who knew it was there.

Image Credits: Unsplash

Content Authenticity Statement: The topic area, key elements to focus on, etc. were decisions made by Braden Kelley, with a little help from Claude to clean up the article.

Subscribe to Human-Centered Change & Innovation WeeklySign up here to get Human-Centered Change & Innovation Weekly delivered to your inbox every week.

Don’t Let Corporate Jargon Hold Your Team Back

Don’t Let Corporate Jargon Hold Your Team Back

GUEST POST from David Burkus

You’re in a meeting. Someone says, “Let’s circle back to ensure alignment on the KPIs so we can really move the needle across products.”

Everyone nods.

But in your head, you’re thinking… “What did they just say?”

That’s corporate jargon. It’s everywhere. Some people love it. Some people hate it. Most of us—well, we just tolerate it. And while jargon isn’t always bad, it can be a bigger problem than we realize. The real issue? When jargon stops making things faster and starts making things foggier. And that fog is slowing your team down.

When Language Obscures, Not Clarifies

Language is supposed to create clarity. It’s meant to connect people, to help them collaborate, and to make smart decisions quickly. But in many organizations, corporate jargon does the opposite. It confuses. It slows people down. And worse, it creates distance—between individuals, teams, and entire departments.

Anthropologist David Graeber explored this in his book Bullshit Jobs, arguing that layers of meaningless work—and meaningless words—emerge in organizations to preserve the illusion of productivity. He called this “managerial feudalism”: leaders expand their scope by hiring people to do questionable work just to increase their headcount. Jargon plays a similar role. The more complex the words, the harder it becomes to question the necessity of the work behind them. But hey, at least it all sounds official, right?

Why We Still Use Corporate Jargon

Here’s the twist: jargon isn’t always a villain.

Research in organizational communication shows that companies adopt specialized language to gain legitimacy. Industry-specific jargon signals expertise. It shows professionalism and alignment with norms. If you’re a doctor, an engineer, or a pilot, technical jargon actually saves time and prevents errors because everyone on the team knows exactly what those terms mean.

But here’s the catch: those teams have a shared understanding.

Inside organizations, that shared understanding often breaks down. Research has also shown that managers who use little to no jargon are actually seen as more trustworthy by employees. In other words, jargon may impress people outside the organization, but inside, it creates headaches.

The real problem isn’t jargon itself—it’s forgetting who you’re talking to.

Know Your Audience

Before you use a term like “OKRs” or “value prop,” pause and ask yourself: Does everyone in this room actually know what that means?

Inside your core team, shared language can be a time-saver. If your product team refers to an MVP, everyone knows you mean minimum viable product—not most valuable player. But when you step outside that team bubble and into a meeting with sales, HR, or external partners, that same shortcut can become a speed bump.

What’s familiar in one department can feel like a foreign language in another. Marketing talks about “demand gen” and “funnels.” IT throws out “DNS propagation.” Finance focuses on “run rates” and “burn.” HR wants to “360” everybody. None of these terms are wrong—but they are highly contextual. And when people don’t know what you mean, they’ll do one of two things: nod and Google it later, or tune out completely.

Here’s a better approach: assume at least one person in the room is hearing the term for the first time. Maybe it’s a new hire. Maybe it’s a partner from another department. Maybe it’s someone from a different industry where that same acronym means something else entirely. Either way, when people feel excluded, they disengage.

The best communicators—and the best leaders—meet people where they are. They don’t oversimplify, but they do make sure no one gets left behind.

Clarity Is a Competitive Advantage

Clarity is kindness.

Whether you’re leading a team or sending a quick email, your words do more than convey information. They shape how people feel about the work—and about you. Nothing slows down a team like a message that has to be reread three times just to be understood. And as communication gets more informal—thanks to Slack, emojis, and even memes—clarity matters more than ever. You don’t need to send GIFs to the board of directors, but you can write like a real person instead of a corporate buzzword generator.

Here’s a simple contrast:

“We’ll leverage our core competencies to achieve stakeholder alignment.”

vs.

“Here’s how we’re using our strengths to meet what our stakeholders need.”

Which one would you rather read?

Clarity doesn’t just improve comprehension—it builds trust. When people don’t have to decode your message, they focus on what you’re actually saying. And they see that you respect their time.

So before you hit send or speak up in a meeting, ask yourself:

  • Would a smart, motivated outsider understand this?
  • Would I say this out loud in a conversation?
  • Can I cut any words without losing meaning?

Nobody ever complains that a message was too clear. Or too short.

Call Out Fake Complexity

Sometimes, jargon isn’t just confusing—it’s a smokescreen. In some organizations, language is used to make something sound more important than it is. If you’ve ever heard a sentence that sounds impressive but doesn’t actually say anything, you’ve seen this in action. Phrases like:

“We’re architecting a holistic transformation framework to unlock cross-functional synergies.”

Sound fancy. But what’s actually happening?

One of the easiest ways to spot unnecessary work—or questionable priorities—is to listen to how people talk about them. If you can’t understand what’s being said, you’re not the problem. The language is.

This is why it’s okay—important, even—to ask, “What does that actually mean?” Or, “Can you give me an example?” You don’t have to be snarky. Just be curious. Either the person will clarify, and everyone will benefit, or they won’t—and you’ve just exposed a deeper issue.

Calling out fake complexity isn’t rude. It’s responsible. It saves time. It protects your team from wasting effort on meaningless work. And as a manager, you set the tone. When you say, “Let’s simplify that,” you give everyone else permission to do the same.

In the end, work that matters doesn’t need to hide behind big words. It speaks for itself.

The Real Role of Corporate Jargon

So let’s be clear: corporate jargon isn’t the enemy. It’s just a tool.

When used with the right audience, it speeds things up. But when it confuses or excludes people, it slows everyone down. The trouble is, jargon tends to creep in during moments of uncertainty. We use it to delay, to mask doubt, or to sound like we’re in control when we’re really just treading water.

But you don’t need jargon to sound competent. You need clarity. Clarity builds trust. Trust builds momentum. And that’s what drives high-performing teams forward.

Image credit: David Burkus

Subscribe to Human-Centered Change & Innovation WeeklySign up here to get Human-Centered Change & Innovation Weekly delivered to your inbox every week.

Scenario Planning for CSOs: Building Multiple Futures into One Strategic Plan

Scenario Planning for CSOs: Building Multiple Futures Into One Strategic Plan

by Braden Kelley and Art Inteligencia

Ask a room of executives whether they do scenario planning and most of them will say yes. Ask to see the scenarios and you’ll usually get three slides: a good case, a base case and a bad case, each one a slightly adjusted version of the same spreadsheet.

I don’t blame them. That’s what the exercise has been reduced to, and a spreadsheet with a pessimistic column isn’t scenario planning. It’s the same future with the volume knob turned up and down.

For a Chief Strategy Officer, the real challenge is a harder one. You have to carry several genuinely different futures in your head, and then produce one strategic plan that doesn’t fall apart if the wrong one shows up. Here’s how I’d approach it.

Why three slides isn’t enough

The good-base-bad structure shares a hidden assumption: that the future differs from your forecast only in degree. A bit better, a bit worse. But the futures that actually blindside organizations are different in kind. A regulation reverses. A customer behavior flips. A competitor arrives from an industry you never watched.

You can’t see a difference in kind by adjusting a growth rate. You only see it by asking what different worlds the signals in front of you could be pointing toward.

Start from signals, not from a template

The most common mistake in scenario work is starting with the scenarios. Somebody picks two big uncertainties, draws a two-by-two grid, and fills in the four boxes with the most vivid story each combination suggests. It looks rigorous. It’s also built on whichever two uncertainties the loudest person in the room happened to pick.

A sturdier method works from the ground up, which is how the [FutureHacking™](https://bradenkelley.com/offerings/futurehacking/) approach is built:

  1. Collect signals. Small, specific observations about what’s changing: a competitor’s strange hire, a policy shift, a customer behavior that doesn’t fit your model.
  2. Group them into trends. The patterns those signals suggest. This is where the team has to argue about what it’s actually seeing.
  3. Build a set of possible futures from the trends. Several, and different enough that each demands a different strategic response.
  4. Decide which future is most probable. Not to bet everything on it, but so you know where your current plan is implicitly wagered.
  5. Choose the future you’d prefer, and map the path. That’s the part that turns a planning exercise into a strategy.

Because every future traces back to real signals, nobody can dismiss one as someone’s pet theory. The argument is about what the evidence suggests, which is a far better argument to have.

The test of a good set of futures

Not every set of scenarios is useful. Here are the questions I’d use to check yours.

Are they different enough? If one strategy works equally well in all of them, you haven’t described different futures. You’ve described one future with different labels.

Can someone defend each one with a straight face? A scenario that’s there only to look balanced, or to scare the board, doesn’t count. Each should be plausible to a thoughtful person in the room.

Does each one change a decision? If you can’t name something you’d do differently in a given future, it’s trivia, not scenario planning.

Is it tied to evidence? Every future should be traceable to signals you can point to.

From many futures to one plan

This is the part most guides skip, and it’s the real CSO problem. You don’t get to run four strategies. You have to deliver one plan. So what does carrying multiple futures into a single plan look like?

Find the moves that work everywhere. Some actions pay off in every future you’ve described. These are your no-regret moves, and they should anchor the plan.

Isolate the bets that depend on one future. Some investments make sense only if one future arrives. Name them as bets, with the future they depend on written next to them. Sometimes the right call is to place the bet. The point is that you’re doing it knowingly.

Build options for the uncertain middle. Where futures diverge, look for ways to buy the right to act later: a pilot, a partnership, a small investment that keeps a door open. Options cost little and are worth a lot if the world tilts your way.

Set tripwires. For each future, decide in advance what you’d have to see to conclude it’s arriving: a metric crossing a threshold, a regulation passing, a competitor making a particular move. Then assign someone to watch for it. A plan that says when to change course is a very different thing from one that hopes it won’t need to.

Done well, you end up with one plan that has a spine of no-regret moves, a short list of explicit bets, a handful of options and a set of tripwires. It’s a living plan that expects to be updated, which is exactly what the annual, single-future version can’t do.

The politics of it

I’d be doing you a disservice if I left out the human side. Presenting multiple futures to a leadership team can feel like admitting you don’t know the answer. Some executives hear “scenarios” and translate it as “indecision.”

The way through is to make the plan firm and the uncertainty explicit. “Here’s what we’re doing no matter what. Here are the bets we’re making and why. Here’s what would make us change our minds.” That isn’t indecision. It’s a level of clarity most single-future plans never reach.

A way to practice

If your team has never built scenarios from the ground up, start with step one. The free FutureHacking Signal Picker helps you identify and prioritize the signals worth watching, which is the foundation everything else rests on. Run it before your next planning cycle and bring the result into the room.

What I’m building next

I’m putting the finishing touches on the FutureCanvas Picker, which takes planners through the full arc: from signals, to trends, to a set of possible futures, to your most probable future, and then to the path toward the future you’d prefer. It’s the closest I’ve come to letting you feel the whole process in a single sitting.

I’m offering early access to a select group first: CSOs, strategic planners and leaders running a planning process right now who can give me honest feedback under real deadline pressure. If that’s you, reach out and let me know and I’ll follow up personally with the select few who get in first.

The plan that survives

The goal of scenario planning was never to predict. It was to build a plan that doesn’t need the prediction to be right. If your current one only works in one future, that’s worth knowing before the future gets a vote.

Image Credits: Pexels

Content Authenticity Statement: The topic area, key elements to focus on, etc. were decisions made by Braden Kelley, with a little help from Claude to clean up the article.

Subscribe to Human-Centered Change & Innovation WeeklySign up here to get Human-Centered Change & Innovation Weekly delivered to your inbox every week.

A Triple-Threat Strategy for Making Progress

A Triple-Threat Strategy for Making Progress

GUEST POST from Mike Shipulski

When you’re looking to make progress, the single most important skill is to see waiting as waiting.

The first place to look for waiting is the queue in front of a shared resource. Like taking a number at the deli, you queue up behind the work that got there first and your work waits its turn. And when the situation turns bad, prioritization meeting spring up to argue about the importance of one bit of work over another. Those meetings are a sure-fire sign of ineffectiveness. When these meetings spring up, it’s time to increase capacity of the shared resource to stop waiting and start making progress.

Another place to look for waiting is the process to schedule a meeting with high-level leaders. Their schedules are so full (efficiency over effectiveness) the next open meeting slot is next month. Let me translate – “As a senior leader and decision maker, I want you to delay the business-critical project until I carve out an hour so you can get me up to speed and I can tell you what to do.” The best project managers don’t wait. They schedule the meeting three weeks from now, make progress like their hair is on fire and provide a status update when the meeting finally happens. And the smartest leaders thank the project managers for using their discretion and good judgment.

A variant of the wait-for-the-most-important-leader theme is the never-ending-series-of-meetings-where-no-decisions-are-made scenario. The classic example of this unhealthy lifestyle is where a meeting to make a decision spawns a never-ending series of weekly meetings with 12 or more regular attendees where the initial agenda of making a decision death spirals into an ever-changing, and ultimately disappearing agenda. Everyone keeps meeting, but no one remembers why. And the decision is never made. The saddest part is that no one remembers that project is blocked by the non-decision.

The first place to look for waiting is the queue in front of a shared resource. Like taking a number at the deli, you line up behind the work that got there first and your work waits its turn. And when the situation turns bad, prioritization meeting spring up to argue about the importance of one bit of work over another. Those meetings are a sure-fire sign of ineffectiveness. It’s time to increase capacity of the shared resource to stop waiting and start making progress.

And the deadliest waiting is the waiting that we no longer see as waiting. The best example of this crippling non-waiting waiting is when we cannot work the critical path and, instead, we work on a task of secondary importance. We kid ourselves into thinking we’re improving efficiency when, in fact, we’re masking the waiting and enabling the poor decision making that starved the project of the resources it needs to work the critical path. Whether you work a non-critical path task or not, when you can’t work the critical path for a week, you delay project completion by a week. That’s a rule.

Instead of spending energy working a non-critical path task, it’s better for everyone if you do nothing. Sit at your desk and play solitaire on your computer or surf the web. Do whatever it takes for your leader to recognize you’re not making progress. And when your leader tries to chastise you, tell them to do their job and give you what you need to work the critical path.

There’s two types of work – value-added work and non-value-added work. Value-added work happens when you complete a task on the critical path. Non-value-added work happens when you wait, when you do work that’s not on the critical path, when you get ready to do work and when you clean up after doing work. In most processes, the ratio of non-value-added to value-added work is 20:1 to 200:1. Meaning, for every hour of value-added work there are twenty to two hundred hours of non-value-added work.

If you want to make progress, don’t improve how you do your value-added work. Instead, identify the non-value-added work you can stop and stop it. In that way, without changing how you do an hour long value-added task, you can eliminate twenty to two hundred hours wasted effort.

Here’s the three-pronged approach for making progress:

Prong one – eliminate waiting. Prong two – eliminate waiting. Prong three – eliminate waiting.

Take the Next Step: Design Out Product Cost

Ready to maximize profit margins and streamline your manufacturing processes? Join us for the interactive webinar, Designing Out Product Cost, and discover battle-tested methods that have boosted profit per square foot by 7X and slashed warranty costs by 4X. You’ll gain access to real-world before-and-after case studies, data-driven design approaches, and practical implementation strategies you can apply right away.

📅 Date & Time: October 29, 2026, at 11:00 AM EST

💵 Investment: $100.00

🎁 Early Bird Bonus: The first 15 registrants receive a complimentary 30-minute 1-on-1 strategy session!

Image credits: Unsplash

Subscribe to Human-Centered Change & Innovation WeeklySign up here to join 17,000+ leaders getting Human-Centered Change & Innovation Weekly delivered to their inbox every week.
Allocate Resources as if People and Planet Matter

Allocate Resources as if People and Planet Matter

GUEST POST from Mike Shipulski

Business is about allocating resources to achieve business objectives. And for that, the best place to start is to define the business objectives.

First – what is the timeframe of the business objectives? Well, there are three – short, medium and long. Short is about making payroll, shipping this month’s orders and meeting this year’s sales objectives. Long is about the existence of the company over the next decade and happiness of the people that do the work along the way. And medium – the toughest – is in-between. It’s neither short nor long but bound by both.

Second – define business objectives within the three types: people, planet and profit.

People. Short term: pay them so they can eat, pay the mortgage and fund their retirement, provide healthcare, provide a safe workplace, give them work that fits their strengths and give them time to improve their community. Medium: pay them so they can provide for their family and fund their retirement, provide healthcare, provide a safer workplace, give them work that requires them to grow their strengths and give them time to become community leaders. Long: pay them so they can pay for their kids’ college and know they can safely retire, provide the safest workplace, let them choose their own work, and give them time to grow the next community leaders. And make it easy.

Planet. Short term: teach Life Cycle Assessment, Buddhist Economics and TRIZ and create business metrics for them to flourish. Medium: move from global sourcing to local sourcing, move to local production, move from business models based on non-renewable resources to renewable resources. Long: create new business models that are resource neutral. Longer: create business models that generate excess resources. Longest: teach others.

Profit. Short, medium and long – focus on people and planet and the profits will come. But also focus on creating new value for new customers.

For business objectives, here’s the trick on timeframe – always work short term, always work long term and prioritize medium term.

And for the three types of business objectives, focus on people, planet and creating new value for new customers. Profits are a result.

Take the Next Step: Design Out Product Cost

Ready to maximize profit margins and streamline your manufacturing processes? Join us for the interactive webinar, Designing Out Product Cost, and discover battle-tested methods that have boosted profit per square foot by 7X and slashed warranty costs by 4X. You’ll gain access to real-world before-and-after case studies, data-driven design approaches, and practical implementation strategies you can apply right away.

📅 Date & Time: October 29, 2026, at 11:00 AM EST

💵 Investment: $100.00

🎁 Early Bird Bonus: The first 15 registrants receive a complimentary 30-minute 1-on-1 strategy session!

Image credits: Gemini

Subscribe to Human-Centered Change & Innovation WeeklySign up here to join 17,000+ leaders getting Human-Centered Change & Innovation Weekly delivered to their inbox every week.
How Should CEOs Operate?

How Should CEOs Operate?

GUEST POST from Geoffrey Moore

A post a little while ago of Dealbook with Andrew Ross Sorkin led off with a great topic: How hands-on should founders be in their companies? As Sorkin notes,

In the framing of Brian Chesky, the Airbnb co-founder and C.E.O., and Paul Graham, the Y Combinator co-founder, it comes down to “founder mode” versus “manager mode.” It’s not a new question — and it draws on longstanding examples like Steve Jobs — but it has taken on fresh significance as start-ups struggle with how to grow while keeping antsy investors happy.

This relates directly to the Zone to Win and the discipline of zone management, so I want to riff off of Sorkin’s column in a Point/Counterpoint way to tease out what I think are the key issues.

My core thesis is that “founder mode” is centered in leadership and is critical to the operating models of the Incubation Zone and Transformation Zone, and that “manager mode” is centered in management and is critical to the operating models of the Performance Zone and Productivity Zone. This is an and, not an or, situation—both are mandatory—but who is in charge where can be up for grabs.

My view, however, is that it should not be. The CEO needs to call the shots when it comes to dealing with disruption and catching the next wave, be that through incubation or transformation. In parallel, the ELT executive suite needs to be in charge of current lines of business in established categories, delivering performance and productivity. The ELT reports to the CEO, so the latter has oversight over the Performance and Productivity Zones and is accountable to the board of directors for their success, but this should largely be accomplished through hiring and promoting the most talented operators, not standing shoulder to shoulder with them on the front lines.

As for the struggle start-ups experience between how to grow and keeping antsy investors happy, the key point is that growth investors are willing to accept short-term shortfalls in financial metrics in order for the enterprise to invest in incubation and transformation initiatives to catch the next wave. Value investors are not. They prefer predictable execution of performance and productivity initiatives that leverage the inertial momentum of established categories. When a high-growth start-up goes public, they get reviewed by financial analysts who are inevitably focused on performance and productivity, and it takes all the narrative skills that the CEO and CFO can muster to build support for any kind of transformation.

Graham, as reported by Sorkin, tells a somewhat different story:

The prime example Graham cited was Chesky. The Airbnb boss shared his story at a recent Y Combinator event, and also discussed it on a podcast: “The less hands-on I was, the more I got sucked into problems. And by the time I got sucked into a problem, it was like 10 times as much work,” Chesky said on the podcast.

Instead, he decided: “I’m going to be involved in every single detail. And Airbnb is not going to do anything more than I can personally focus on.”

That has gotten results, Graham wrote, with Airbnb now having some of the best free cash flow in Silicon Valley. Then again, Airbnb’s stock price is 31 percent below its 52-week high.

Okay, there’s a lot to unpack here. Brian, in my view, is a great CEO leader. The fact that he got sucked into a lot of problems, I suspect, is not because his team does not know how to manage but because the category itself is transitioning from hypergrowth to growth, the competition is catching up, the regulators are weighing in, and so there is still a lot of pathfinding to do. As these paths become more established, he should deliberately step away from those operations to free himself for the next wave of changes. The fact that the company’s stock price is 31 percent below its 52-week high, given that Airbnb has great free cash flow, is far more likely to be due to category dynamics than management execution.

Sorkin goes on to list a number of well-known examples of CEOs, in addition to Jobs, who have taken a very hands-on approach to management, including Jensen Huang, Elon Musk, Mark Zuckerberg, and Sam Altman. All, however, are living in the midst of categorical disruption, where leadership takes precedence over management. That is because categorical stability and inertial momentum, which are the prerequisites for management success, are simply not there yet.

Sorkin also mentions Howard Schultz, who built Starbucks from a local Seattle coffee chain into a global colossus and was famously hands-on, also fits the mold. But here I think we have a CEO who has not orchestrated the transition to management well, witnessed by the volatility in its stock price for the first half of this decade, in a category that is not under disruption.

Finally, there are a handful of examples at the end of the column that can serve as litmus tests for zone management principles:

Dan Rose, who held leadership positions at Amazon and Meta, wrote that Jeff Bezos and Zuckerberg “were both micro-managers, deep in the details of the product and business. They never set expectations of autonomy, and they fired anyone who resisted their oversight.”

Amazon has never stopped disrupting, and the core of its innovation engine, and Bezos’s personal genius, is an incredibly deep and fine-grained inspection of established processes which underpins their radical reengineering to generate astounding competitive advantage. Meta is more of a mixed bag, but again, with a quarter of the Earth’s population on the platform, it is in the midst of every disruption on the planet. The idea that management should have autonomy under such conditions is ludicrous.

Others said there were nuances. Jessica Lessin, the founder of The Information, argued that founders do need capable managers, noting that Jobs relied on Tim Cook to oversee the vast and intricate manufacturing operation that became one of Apple’s most crucial assets. A start-up investor, Henrik Torstensson, agreed that execution mattered, citing Microsoft under Satya Nadella as a “Hall of Fame example” of manager mode done right.

In both instances, Apple and Microsoft are leveraging well-established businesses in personal computing, supplemented by Apple’s success in smartphones and media distribution, and Microsoft’s in business applications and, most recently, cloud computing, while at the same time engaging with the category disruption of AI. This calls for a balance of leadership and management, which is Satya’s gift. Tim has a tougher hand to play because Steve is an impossible act to follow. But since they are running two of the most valued companies on the planet, I think they are probably doing OK.

Stepping back from this whole line of thinking, the key takeaway is that the discipline of zone management is well-equipped to deal with these challenges. The first question to answer is not who should be in charge, but rather, how should we tackle this? What zone, in other words, offers the best operating model for coping with the challenges at hand? Once we decide that, then we know whether leadership or management gets the primary nod, and, thus, whether the CEO or the ELT should take the reins.

That’s what I think. What do you think?

— Image credit: Geoffrey Moore

Subscribe to Human-Centered Change & Innovation WeeklySign up here to join 17,000+ leaders getting Human-Centered Change & Innovation Weekly delivered to their inbox every week.
Why the Incredible GE Turnaround Could be a Sign of the Times

Why the Incredible GE Turnaround Could be a Sign of the Times

GUEST POST from Greg Satell

When Jack Welch took the helm at General Electric in 1981, it marked the beginning of a new era. Corporations would no longer coddle workers, but would slash costs, close factories and focus on increasing shareholder value. By 1999 he had increased revenues from $26.8 billion to nearly $130 billion and in 2000 he was named “Manager of the Century” by Fortune magazine.

Yet all the success belied serious problems rumbling underneath the surface. As David Gelles explains in, The Man Who Broke Capitalism, Welch increased profits largely by “financializing” the firm and operations suffered. Under his successor, Jeffrey Immelt, GE collapsed and was removed from the Dow index.

Yet while Welch’s rise marked a new era of shareholder capitalism, the new CEO at GE, Larry Culp has taken a different turn. He invests in workers, distributes authority and has refocused the firm on improving manufacturing productivity. The result has been one of the most dramatic turnarounds in industrial history, perhaps signaling a larger shift.

The Welch Myth

To understand why the Welch era was not what it seemed, let’s look at one common practice that took hold in the 1980s and 90s: Offshoring. From a shareholder value perspective, it has an intuitive logic. You move your factory from high wage countries such as the US to low wage countries such as China and pocket the savings. You lower costs and increase profits, at least in the short-term.

Yet that analysis omits some important factors. First of all, it undermines trust among employees, suppliers and other partners when relationships are treated as purely transactions. Also, a Harvard study found that moving the factory floor thousands of miles away from R&D reduces knowledge transfer and has a negative effect on innovation.

Looking back, it’s easy to see how this played out at GE. The company became more profitable, but less productive. For decades, it failed to innovate. Its last major invention was the CT scanner, which came out in the 1970s, before Jack Welch took the helm. For all of the hype about his management genius, in truth Welch was, in large part, living off the accomplishments of his predecessors.

One helpful way to look at managing an enterprise is to group it into two major activities: capacity building and optimization. Building capacity is a drag on profits in the short term, but builds a foundation for the future. Optimization focuses on efficiency, which drives short-term profits, but doesn’t build anything for the long term.

Welch’s layoffs created profits, but undermined GE’s ability to build capacity. The firm’s increasing reliance on its finance arm to smooth earnings masked real problems and increased risk. The stage was set for a downfall.

The Road To Ruin

In 2001, after a lengthy succession process, Jeffrey Immelt was named Jack Welch’s successor and he began his star-crossed tenure. The 9-11 attacks hit the firm’s aerospace business hard and, while he used many of the same accounting tricks involving GE finance that Welch employed, the share price continued to lag. That’s when Jeffrey Immelt set out on a journey to transform GE into a 124 year old startup.

No longer would GE be a boring old manufacturing company, but would make a “pivot” to the digital age. Although it was one of the largest private organizations in the world, with 300,000 employees, he sought to become agile and nimble enough to compete with high-flying Silicon Valley firms. A key ambition was the development of Predix, an industrial software platform.

He also brought in Lean Startup guru Eric Ries to help instill a more entrepreneurial culture and speed time to market. The initiative caught on and eventually became the FastWorks program, One of the most touted projects was the development of a gas turbine , which reduced development time by a full year while significantly increasing performance. Immelt also acquired the power division of Alstom, essentially doubling down on the same bet.

It didn’t end well. As renewable energy began to take off, demand for gas turbines declined markedly. In 2017, problems in the firm’s power division led to massive layoffs and GE’s removal from the Dow after 110 years.. Immelt was forced to step down as CEO. The company, once famous for its sound management, was now an iconic failure.

The Rebirth

In the aftermath of GE’s collapse, Larry Culp was named as the first outsider CEO in its history and he came with a very different approach. Unlike Jack Welch, he didn’t take pride in layoffs or try to be a management guru. Nor did he fall in love with Silicon Valley and fashion himself as some sort of new age hero, like Jeffrey Immelt.

Instead, he focused on improving operations through lean manufacturing, a methodology focused on continuous improvement that’s been around for over four decades, and shed debt to improve the resiliency of its balance sheet. He also broke the company up into three separate firms, reversing GE’s history of growth through acquisition.

Most of all, he shifted management’s focus from seeing its employees as cost centers to profit centers. Rather than offshoring to cut costs, lean manufacturing puts an emphasis on getting the factory floor involved, using frontline hands-on knowledge to improve productivity and efficiency. GE’s famous culture of stack-ranking and shooting the messenger has been replaced by one in which workers are encouraged to report problems so they can be solved.

The results are hard to argue with. In 2023, GE’s share price leaped by 95.8%, outperforming darlings such as Apple, Google and Microsoft and sending its market cap back over $150 billion. Perhaps most importantly, he’s shown that you can best serve shareholders by serving employees, much as MIT’s Zenep Ton argues in her book, The Case for Good Jobs.

Rethinking American Industry

General Electric has long been symbolic of the US economy. Formed in the 1890s when J.P. Morgan merged Thomas Edison’s electric company with other firms, it was one of the original components of the Dow Jones index and signaled America’s industrial rise. It also became the first major conglomerate, forming the Radio Corporation of America (RCA) in 1919, which became a leading broadcaster.

That all began to change when Jack Welch took over in 1981. He led a new era of “Welchism,” in which CEO’s laid off employees, offshored factories and engaged in “financial engineering,” to goose profits. American industry followed suit, cutting investment in R&D, lobbying hard for cuts in government spending and corporate taxes, hollowing out the US industrial base.

Yet it appears that GE’s new CEO, Larry Culp, might be as emblematic for the new era as Jack Welch was for the old one. Instead of layoffs, he’s investing in lean manufacturing methods that put front-line workers at the center and instead of using acquisitions to fuel growth, he’s broken the company up to help focus on operational excellence.

This reflects a greater shift that began during the Obama Administration with the creation of the Advanced Manufacturing Office and the Manufacturing USA Institutes. It has continued under the Biden Administration with legislation such as the CHIPS Act and the IRA. The results are clear. Manufacturing employment has increased by roughly 1.5 million jobs since 2010, productivity is up and unemployment is at record lows.

The truth is that we’re moving from an era of bits to an era of atoms and that means we can’t just move fast and break things anymore. We can expect the basis of competition to shift away from design sprints, iterating, and pivoting to building meaningful, collaborative relationships in order to solve grand challenges.

Once again, what’s going on at GE might be a sign of the times.

— Article courtesy of the Digital Tonto blog
— Image credit: 1 of 1,550+ FREE quotes for you at http://misterinnovation.com

Subscribe to Human-Centered Change & Innovation WeeklySign up here to join 17,000+ leaders getting Human-Centered Change & Innovation Weekly delivered to their inbox every week.