Author Archives: Geoffrey Moore

About Geoffrey Moore

Geoffrey A. Moore is an author, speaker and business advisor to many of the leading companies in the high-tech sector, including Cisco, Cognizant, Compuware, HP, Microsoft, SAP, and Yahoo! Best known for Crossing the Chasm and Zone to Win with the latest book being The Infinite Staircase. Partner at Wildcat Venture Partners. Chairman Emeritus Chasm Group & Chasm Institute

20 Philosophical Questions to Wrap Your Head Around

20 Philosophical Questions to Wrap Your Head Around

GUEST POST from Geoffrey Moore

MSN published a piece with this title, and I am complete sucker for such things, mainly as a way to pressure test the views I express in The Infinite Staircase. I plan to answer as many of these questions as I can, one at a time, and invite you to follow along to play the same game in parallel with your own ideas about what’s what.

Today’s Topic? What is the true essence of reality? You gotta love a question that has three words in it, true, essence, and reality, none of which are readily definable! Here’s the paragraph that follows:

The article titled ‘What Is the True Nature of Reality?‘, published on the Curious Matrix website, explains how throughout history countless philosophers and scientists have grappled with the mysteries of reality. Their exploration encompasses both the realm encompassing matter and particles as well as the intangible aspects of existence. This philosophical dualism has sparked an array of probing questions; What truly constitutes the essence of the mind? How does it relate to the body? Do they exist independently? When we ponder the nature of the reality we inevitably question our perceptions. Contemplate the very core of existence.

By the way, it is worth clicking through to read that article because it goes way beyond the mind/matter dualism that is summarized above. Setting that aside, however, how should we reply to the question itself? Note that it has changed the phrasing from “true nature of reality” to “true essence of reality” which actually makes a difference, and I am going to stick with the former because the latter makes the assumption that reality coalesces into an essence, which is not something I can agree to.

My answer is that the true nature of reality is a hierarchy of systems, each one of which emerges from the ones prior, with no top or bottom system clearly in view. In The Infinite Staircase I make the case for a stack of eleven such systems, beginning with three at the bottom that are materialistic in nature (physics, chemistry, and biology), all of which are all governed by the Second Law of Thermodynamics, or what I call the metaphysics of entropy. These are followed by four systems that are organic in nature (desire, consciousness, values, and culture), representing the evolution of life prior to the arrival of mankind, all governed by the dynamics of natural and sexual selection, or what I call the metaphysics of Darwinism. Those underpinnings tee up the topmost set of systems. ones that are distinctively human in nature (language, narrative, analytics, and theory), all governed by symbols and symbolism, or what I call the metaphysics of memes.

The advantage of this framework is that, instead of limiting ourselves to one or two foundations, we can refer to any of eleven possible platforms, alone or in combination with others, to explain any particular aspect of reality. Here’s how one might take advantage of this to answer the questions that are embedded in the latter half of the paragraph quotes above.

What constitutes the essence of mind? Mind is made up of multiple systems in the staircase, but the primary two are narrative and analytics, both leveraging the system of language. That is, most of our conscious experience is taken up with us telling stories to others or to ourselves and processing those stories to extract knowledge or entertainment. In support of this activity, our minds are powered by our brains, hence involving the stairstep of consciousness and all the material systems below it, so no, our minds cannot be independent of our bodies. At the same time, minds are socially developed, bringing in the stairsteps of values, culture, and language.

In sum, the true nature of our minds is that they are a layer cake of systems interoperating with one another in service to us executing our strategies for living. The fact that we have success in these efforts is demonstrated by the real-world outcome of our continued existence. This suggests that we have no pressing need to question our perceptions. The thing to question instead is the notion that there is a “very core” to our existence, a true essence of reality. That concept is way too monistic, given the complexity of the system’s hierarchy and its interdependent operations.

That’s what I think. What do you think?

— Image credit: Gemini

Subscribe to Human-Centered Change & Innovation WeeklySign up here to join 17,000+ leaders getting Human-Centered Change & Innovation Weekly delivered to their inbox every week.

How Should CEOs Operate?

How Should CEOs Operate?

GUEST POST from Geoffrey Moore

A post a little while ago of Dealbook with Andrew Ross Sorkin led off with a great topic: How hands-on should founders be in their companies? As Sorkin notes,

In the framing of Brian Chesky, the Airbnb co-founder and C.E.O., and Paul Graham, the Y Combinator co-founder, it comes down to “founder mode” versus “manager mode.” It’s not a new question — and it draws on longstanding examples like Steve Jobs — but it has taken on fresh significance as start-ups struggle with how to grow while keeping antsy investors happy.

This relates directly to the Zone to Win and the discipline of zone management, so I want to riff off of Sorkin’s column in a Point/Counterpoint way to tease out what I think are the key issues.

My core thesis is that “founder mode” is centered in leadership and is critical to the operating models of the Incubation Zone and Transformation Zone, and that “manager mode” is centered in management and is critical to the operating models of the Performance Zone and Productivity Zone. This is an and, not an or, situation—both are mandatory—but who is in charge where can be up for grabs.

My view, however, is that it should not be. The CEO needs to call the shots when it comes to dealing with disruption and catching the next wave, be that through incubation or transformation. In parallel, the ELT executive suite needs to be in charge of current lines of business in established categories, delivering performance and productivity. The ELT reports to the CEO, so the latter has oversight over the Performance and Productivity Zones and is accountable to the board of directors for their success, but this should largely be accomplished through hiring and promoting the most talented operators, not standing shoulder to shoulder with them on the front lines.

As for the struggle start-ups experience between how to grow and keeping antsy investors happy, the key point is that growth investors are willing to accept short-term shortfalls in financial metrics in order for the enterprise to invest in incubation and transformation initiatives to catch the next wave. Value investors are not. They prefer predictable execution of performance and productivity initiatives that leverage the inertial momentum of established categories. When a high-growth start-up goes public, they get reviewed by financial analysts who are inevitably focused on performance and productivity, and it takes all the narrative skills that the CEO and CFO can muster to build support for any kind of transformation.

Graham, as reported by Sorkin, tells a somewhat different story:

The prime example Graham cited was Chesky. The Airbnb boss shared his story at a recent Y Combinator event, and also discussed it on a podcast: “The less hands-on I was, the more I got sucked into problems. And by the time I got sucked into a problem, it was like 10 times as much work,” Chesky said on the podcast.

Instead, he decided: “I’m going to be involved in every single detail. And Airbnb is not going to do anything more than I can personally focus on.”

That has gotten results, Graham wrote, with Airbnb now having some of the best free cash flow in Silicon Valley. Then again, Airbnb’s stock price is 31 percent below its 52-week high.

Okay, there’s a lot to unpack here. Brian, in my view, is a great CEO leader. The fact that he got sucked into a lot of problems, I suspect, is not because his team does not know how to manage but because the category itself is transitioning from hypergrowth to growth, the competition is catching up, the regulators are weighing in, and so there is still a lot of pathfinding to do. As these paths become more established, he should deliberately step away from those operations to free himself for the next wave of changes. The fact that the company’s stock price is 31 percent below its 52-week high, given that Airbnb has great free cash flow, is far more likely to be due to category dynamics than management execution.

Sorkin goes on to list a number of well-known examples of CEOs, in addition to Jobs, who have taken a very hands-on approach to management, including Jensen Huang, Elon Musk, Mark Zuckerberg, and Sam Altman. All, however, are living in the midst of categorical disruption, where leadership takes precedence over management. That is because categorical stability and inertial momentum, which are the prerequisites for management success, are simply not there yet.

Sorkin also mentions Howard Schultz, who built Starbucks from a local Seattle coffee chain into a global colossus and was famously hands-on, also fits the mold. But here I think we have a CEO who has not orchestrated the transition to management well, witnessed by the volatility in its stock price for the first half of this decade, in a category that is not under disruption.

Finally, there are a handful of examples at the end of the column that can serve as litmus tests for zone management principles:

Dan Rose, who held leadership positions at Amazon and Meta, wrote that Jeff Bezos and Zuckerberg “were both micro-managers, deep in the details of the product and business. They never set expectations of autonomy, and they fired anyone who resisted their oversight.”

Amazon has never stopped disrupting, and the core of its innovation engine, and Bezos’s personal genius, is an incredibly deep and fine-grained inspection of established processes which underpins their radical reengineering to generate astounding competitive advantage. Meta is more of a mixed bag, but again, with a quarter of the Earth’s population on the platform, it is in the midst of every disruption on the planet. The idea that management should have autonomy under such conditions is ludicrous.

Others said there were nuances. Jessica Lessin, the founder of The Information, argued that founders do need capable managers, noting that Jobs relied on Tim Cook to oversee the vast and intricate manufacturing operation that became one of Apple’s most crucial assets. A start-up investor, Henrik Torstensson, agreed that execution mattered, citing Microsoft under Satya Nadella as a “Hall of Fame example” of manager mode done right.

In both instances, Apple and Microsoft are leveraging well-established businesses in personal computing, supplemented by Apple’s success in smartphones and media distribution, and Microsoft’s in business applications and, most recently, cloud computing, while at the same time engaging with the category disruption of AI. This calls for a balance of leadership and management, which is Satya’s gift. Tim has a tougher hand to play because Steve is an impossible act to follow. But since they are running two of the most valued companies on the planet, I think they are probably doing OK.

Stepping back from this whole line of thinking, the key takeaway is that the discipline of zone management is well-equipped to deal with these challenges. The first question to answer is not who should be in charge, but rather, how should we tackle this? What zone, in other words, offers the best operating model for coping with the challenges at hand? Once we decide that, then we know whether leadership or management gets the primary nod, and, thus, whether the CEO or the ELT should take the reins.

That’s what I think. What do you think?

— Image credit: Geoffrey Moore

Subscribe to Human-Centered Change & Innovation WeeklySign up here to join 17,000+ leaders getting Human-Centered Change & Innovation Weekly delivered to their inbox every week.

Mixed Reality Headsets Meet the Dead Zone

Mixed Reality Headsets Meet the Dead Zone

GUEST POST from Geoffrey Moore

My colleague and social media maven, Rich Stimbra, forwards me news items that might spark a blog post, like the following a couple of years ago:

Meta has scuttled development of a high-end mixed-reality headset meant to compete with Apple’s Vision Pro starting in 2027, The Information reports, citing anonymous sources. Production cost was a primary factor, since Meta was using the same micro OLED display tech as Apple, but trying to keep the headset under $1,000 in order to attract buyers. Apple’s $3,500 Vision Pro, meanwhile, is “stuck in neutral,” per Business Insider. Falling U.S. sales will be offset somewhat by its international launch in June, but the Vision Pro has no must-have app yet — and a more affordable model is expected next year.

This was clearly a technology adoption problem, and clients often ask members of The Chasm Group how you can tell where a given category is in the Technology Adoption Life Cycle, and how should that impact your commitment to the opportunity?

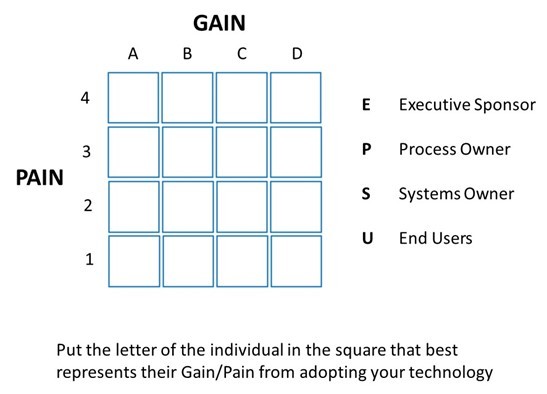
One tool we use is called the Pain/Gain matrix, as illustrated in the two charts that follow. The first chart tees up a thought experiment exercise. Looking at the disruptive innovation you are seeking to bring to market, ask yourself how much gain does it deliver, and how much pain must the customer go through to get it? In so doing, don’t just consider the end user, also take into account the other constituencies that must support the purchase. This is particularly germane to B2B enterprises, so you have to squint a bit to apply it to consumer markets. That said, here is the framework:

Pain Gain Matrix

The executive sponsor is the one who has to pay for this, the process owner is the one who has to secure the productivity improvement from it, the systems owner is the one who has to install and support it, and the end user is the one who has to actually extract the benefits from it. Each one has their own pain/gain experience, so they need to be placed separately. (In consumer markets, all four roles could condense into one, although in many families they may be distributed across either one or both parents as well younger and older siblings.)

The goal of the thought experiment is for the team to reach a consensus on the most likely square for each of the four stakeholders based on the current offer in the market today. Once you have all four placed in one (and only one) square, then you can turn to the second chart, which serves as a kind of decoder ring in that it predicts where you are likely to be in the adoption life cycle and what you will have to do to be successful at that stage.

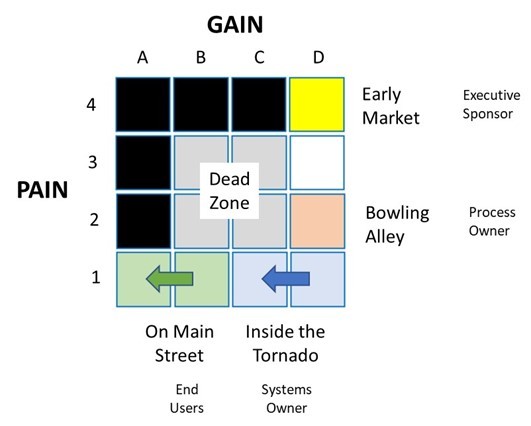
Dead Zone Matrix

Following the Technology Adoption Life Cycle around the edges of the diagram

One might expect that the life cycle would proceed from the upper right to the lower left on a diagonal path, a straight line being the shortest distance between two points. It turns out that is not the case.

For the Early Market, a high-pain, high-gain proposition is OK provided the size of the gain is massive. That is, if you can deliver a truly transformative outcome, early adopters are willing to put up with a considerable amount of pain (and expense) to get it. However, if it is anything less than truly transformative, then they won’t play. That is why the winning Early Market operating model is a bespoke project wherein you and they put serious skin in the game, including assigning your best and brightest to the effort and simply refusing to stop until you have got the thing all the way to bright. The key to this stage is to have a visionary executive sponsor who will commit not only to fund the outcome but to continue to support it through its struggles until it gets all the way to the finish.

For the Bowling Alley (including the critical crossing the chasm step) the critical issue is still very much the size of the gain, what we call the compelling reason to buy, but the ability to absorb pain is much less. Here we have a pragmatist process owner who is under direct pressure to fix a broken mission-critical process that they cannot remediate with conventional solutions. They are desperate for a solution to their problem, what we call the whole product, which will be a huge gain for them. However, they do not have the resources to fund a bespoke project, which means they cannot absorb a great deal of pain. As a result, the vendor has to bring the whole product to them, partners included, and keep everyone committed to stay the course until the fix is up and running and proven successful. The process owner is willing to pitch in here, and so can absorb some pain in order to get to their goal, but nowhere near as much as the Early Market visionary executive.

For a Tornado to form, two things must change. The first is the emergence of a killer app that makes everyone and their mother want the new thing—that’s the big gain that has broad appeal. The second is that there has to be a major reduction in pain—a big drop in the friction that has been holding the category back to date. The goal is to sell a stripped-down, friction-free killer app that has a super-short time to value and then expand over time to address adjacent opportunities that may require more development but which can be readily absorbed because the core product is already installed. During the Tornado proper, particularly at its outset, it is the systems owners who are under the gun to procure and deploy the killer app as fast as possible. Their speed is gaited by whatever friction is still present, so the more this can be removed, the faster the tornado can spin up and the further it can spread. The company that does this best typically takes the field, becomes installed as the category gorilla, and generates outsized returns for many years to come.

Finally, when technology adoption comes to Main Street, we are now in the expand part of the land-and-expand playbook, where the gaiting item is how many different use cases it can support in how many different contexts and whether the offer can be converted from a licensable product to a consumable service. Under such conditions, because the amount of pain to adopt has been reduced to a bare minimum, it takes less and less gain to drive additional market growth. The end users are the ones who most benefit, and success rides increasingly on securing distribution channels that get to them as directly as possible and making it as easy as pie for them to try and buy, or at least try and then get their system owner to buy.

The Dead Zone

As you can see, the Life Cycle follows a path from the upper right to the lower left of the diagram by skirting around the edges. What about all the other squares?

Well, the ones that are blacked out are simply non-starters. The pain exceeds the gain to the point that no one other than a technology enthusiast would want to engage. But the four squares in the very center of the diagram are the ones that are the most dangerous. Collectively they make up the Dead Zone, which is another way of seeing the chasm, or what Intel used to call the Valley of Death.

Products in the Dead Zone deliver good (but not amazing) gains, but they do so at the cost of real (although not excruciating) pain. This combination is the kiss of death. It causes prospective customers to express real interest in the offer (“We’d love to take a meeting and see a demo”), but it does not motivate them sufficiently to get them to actually buy. It is hard to imagine a greater waste of go-to-market resources than that. Start-ups, as well as in-house incubations who venture out into such a desert usually die of thirst, meaning they don’t get that life-supporting next round of funding.

It is kind of like a LaBrea Tar Pit that swallows up whole species, as witnessed by the Sharp’s Personal Digital Assistant, RCA’s 8-track tape, and Mazda’s rotary automobile engine, as well as the . . .

Mixed Reality Headset

This sucker has Dead Zone written all over it. And because it is being positioned as a consumer product, it has a much tougher row to hoe. There is simply no chance of it getting traction unless and until someone can bring to market a killer app at a consumer price point, which will require some very deep pockets to get there, not to mention incredible design skills to get it right.

A much slower but more achievable path would target a B2B customer base with Bowling Alley applications that address urgent problems with mission-critical business processes. An obvious example relates to the “aging out of the workforce” problems that industrial manufacturers are facing, both in the factory and in field services. There simply are not enough trained technicians to meet the need, especially now that many of these industries are moving back onshore. Mixed reality headsets can be used to enable just-in-time training for onboarding inexperienced workers better, faster, cheaper, and even more importantly, safer than conventional alternatives.

Is this a killer app? Heck no, but it is a start; it can support a higher price point, and it can create enough volume to warrant investing in lower-cost approaches. What it cannot do is be rushed. The biggest cause of Dead Zone casualties is a management team that thinks a tornado is upon them when in fact it is just a Hype Cycle hitting its peak.

That’s what I think. What do you think?

— Image credit: Pexels, Geoffrey Moore

Subscribe to Human-Centered Change & Innovation WeeklySign up here to join 17,000+ leaders getting Human-Centered Change & Innovation Weekly delivered to their inbox every week.

AI and the Enterprise

Quo Vadis?

AI and the Enterprise

GUEST POST from Geoffrey Moore

Everybody gets that AI is going to change the world, but nobody is really clear as to how, which would be OK except that CIOs everywhere are under pressure to invest now, at a time when things are still forming, norming, and storming. We need to step back for a moment and survey the landscape so we can prioritize where we should engage first and why.

Let me suggest the following framework as a point of departure:
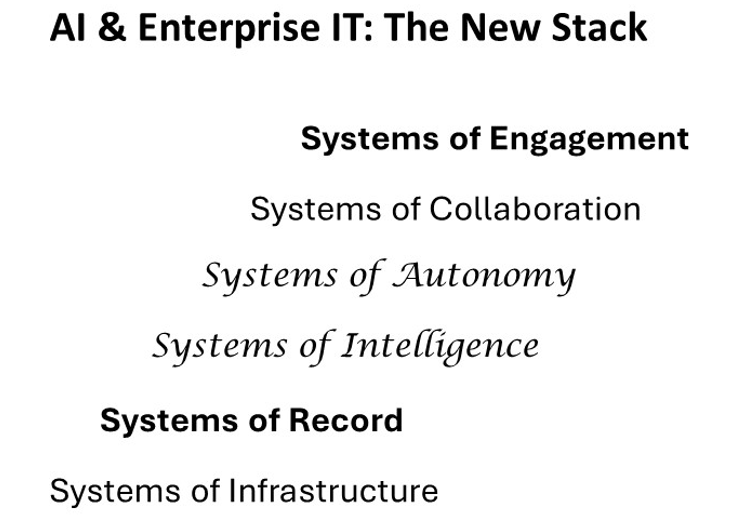
I submit that most of the value of enterprise IT today is delivered by the two systems highlighted in bold—the systems of record, which include finance, HR, supply chain, purchasing, and the like, and the systems of engagement, which include sales, service, marketing, commerce, and the like. These are the mission-critical stakeholder systems that define every enterprise’s relationship with its customers, partners, investors, regulators, and employees. They are quite simply indispensable, and as such, they are the anchor tenants of the Stack, with all the other elements ultimately justifying their existence by being in service to one or the other of the two.

Both systems rose to prominence in the 1990s as client-server applications running atop the Internet, and in this century, they have been advanced dramatically by two sets of adjacent sets of systems, the systems of infrastructure, which include cloud computing, mobile computing, data management, cybersecurity, and hyperscale outsourcing on demand, and the systems of collaboration, which include video conferencing, file sharing, messaging, threaded discussions, e-signatures, and the like. These have enabled companies to expand both the external reach of their systems of engagement and the internal productivity of their systems of record.

Now, we are seeing the emergence of a third set of systems, still nascent, consisting of systems of intelligence, which include predictive AI and generative AI, and systems of autonomy, which include agents. Both are based on advanced statistical software that can learn, and both are driven by machine learning feasting on all the data it can hoover up, including massive troves of log files that were never before examined except forensically.

The question before us is how will systems of intelligence and systems of autonomy impact the operation of the Stack as we have known it to date.

The first claim of this framework is that the AI-enabled systems will operate in the middle of the Stack, not at the top, and not at the bottom. That is, they will not displace any of the other systems but rather, will enhance them dramatically by operating behind the scenes. To get to more specific claims, let’s look at each layer of the stack one at a time.

Systems of Infrastructure

With respect to our systems of infrastructure, the most astounding impact of AI to date is the realization of just how much compute and storage it can consume. To generate a competitive Large Language Model (LLM) requires a hyperscale compute footprint that only a handful of companies have the resources to deploy. When we hear that Microsoft has invested $13 billion in OpenAI, we can rest assured that the bulk of that will come in the form of compute service. Ditto for Amazon, Meta, and Google.

Everyone else will need to license one or more of these LLMs and then adapt it for use in their own Stack. These adaptations, in turn, will rely heavily on first-party data from the enterprise’s own systems of record and engagement, supplemented by data from their systems of collaboration, as well as licensed second-party data, and publicly available third-party data. Extracting all that data, normalizing the metadata, filtering out the information that is protected by data sovereignty regulations, and staging the rest in a data lake for real-time use cases represents the most immediate challenge for CIOs today.

For many real-time applications in the physical world, latency issues will dictate that some processing needs to be done at the edge rather than in the core. This calls for a new kind of PC server armed with a GPU as well as a CPU, running a real-time operating system, connected under next-generation cyber-security protection. By contrast, digital-only applications for the virtual world, including most use cases for systems of record and systems of engagement, require modest infrastructure changes, if any. The current generation of co-pilots all run on the current end-user platforms, with the heavy lifting all being done by either in the core.

Systems of Record

Systems of Record, as we have already noted, are the foundation of enterprise operations. They are intentionally conservative by design. This ensures their integrity, but at the expense of ease of use and adaptability to circumstance. AI changes this game dramatically.

Generative AI augments the click-based UI of the core system, which users need to be trained on, with a natural language interface that is much more forgiving and can be learned through trial and error. Advanced use cases can be created through prompt engineering, allowing a general-purpose LLM to be used in tandem with proprietary enterprise data to ensure privacy, integrity, and relevance. These prompts can be reused and are likely to become an important reservoir of trade secrets.

Predictive AI is an even bigger game-changer. We have been doing this long before the current AI wave but via software that is preprogrammed and does not learn. Machine learning allows for continuous discovery of next-best actions, be they for predictive maintenance, fraud detection, energy optimization, demand forecasting, or product sourcing. It is like having a six-sigma black belt on duty 24/7.

Agents are a bit more dicey, particularly for regulated applications or ones that pose liability issues. Here a human-in-the-loop co-pilot model is likely to prevail for a long time to come, even after it has been shown conclusively that agents can do the job as well as, or even better than, humans. Think X-ray diagnosis or self-driving cars.

Systems of Engagement

We are skipping up to the top because systems of record and systems of engagement have much in common. That said, they are less conservative because they must continuously adapt to unpredictable workflows based on prospect, customer, transaction type, market, and use-case.

Generative AI has a much bigger role to play in these market-facing applications because, in addition to all the UI benefits mentioned earlier, it can actually substitute for human beings in Level One interactions, including creating and running email marketing campaigns, fielding customer service requests through both email and chat, supplying field engineering professionals with on-demand technical support information, alerting sales professionals to next-best actions, and the like.

Predictive AI, on the other hand, is more of a stretch because human factors are less predictable than system behaviors. Nonetheless, data-driven decision-making trumps intuition in the long run, and advanced statistical software that learns outperforms even the best humans eventually, as our friends at DeepMind taught us with respect to the game of Go. Sales forecasting and market campaign attribution are two areas in particular where there is low-hanging fruit to pick. It just takes more patience and, given the reputational risks involved in market-facing interactions, a more prudent approach to rolling anything out at scale.

Agents fall somewhere in between in that, for highly routine interactions, they can shine and actually provide better customer service than humans, as we all learned many years ago from ATM machines who trumped in-bank tellers from day one. One thing to guard against here is to measure the success of such programs by cost savings instead of friction reduction, the latter creating a much bigger payoff in customer loyalty, active use, and churn reduction.

Finally, co-pilots for all customer-facing functions are really a no-brainer. They do not lose context, they do not lose track of time, and they do not get bored with routine. In addition, they are great at prompting and taking a first cut at any natural language task. The critical issue here is focus. The more tuned the co-pilot is to your specific business, the more impactful its contributions will be.

Systems of Collaboration

First of all, we need to appreciate the fact that systems of collaboration are a differentiating source of information for any enterprise. That is, more than any other source, they represent the quality and texture of all your relationships in flight, not just their progress toward achieving your targeted outcomes. They embody who you are and what you care about. By including such data in data lakes that feed your AI models, not only will you improve your systems of collaboration themselves but also make better recommendations to your systems of record and engagement.

Specific to improving collaboration itself, AI excels at summarizations that cut through the clutter of long communication threads, timely reminders that keep workflows from bogging down, and sentiment analyses that can detect concerns and improve tone. The more your enterprise depends on nuanced knowledge work, the higher such improvements need to be on your priority list.

Systems of Intelligence

As you can see from the foregoing, in my view, we should not think of systems of intelligence as a separate layer in the Stack but rather as a technology infusion that changes its very nature. That is, our core business systems are poised to become more intelligent. Indeed, a fruitful metric might be something like a “system IQ test,” which CIOs could use both to assess their current state and to target their future state, all to be done by overlaying and integrating a layer of advanced statistical software that learns. As the BASF slogan used to say, “We don’t make the product, we make it better.”

What we should not endorse is the notion that Systems of Intelligence, or indeed any form of AI, is going to “take over.” Yes, they could have unintended consequences, but no they could not have Game of Thrones ambitions.

With one possible exception.

Systems of Autonomy

Systems of autonomy are the natural extension of systems of intelligence wherever the task in question can be done better by a machine than a person. We use them to place digital advertising, to get astronauts to space stations, to orchestrate the Internet, to run the GPS applications that help us navigate the world, to detect military threats, to prevent spam. They are an indispensable part of the digital transformation we are still in the midst of, and their role will only increase going forward.

The question is when you take the human out of the loop, who or what is in charge? This is not an intractable problem, but it is also not one that will get solved theoretically. This one will require lived experience, a history of successes and blunders, some pleasant surprises, and some very unpleasant unintended consequences. We should not be shocked. Life never stops evolving, and natural selection never stops operating. We just need to step up.

That’s what I think. What do you think?

— Image credit: Gemini, Geoffrey Moore
Subscribe to Human-Centered Change & Innovation WeeklySign up here to join 17,000+ leaders getting Human-Centered Change & Innovation Weekly delivered to their inbox every week.

The Language of Thought

The Language of Thought

GUEST POST from Geoffrey Moore

Where do thoughts come from? Is there any structure to them before they manifest themselves in language? Is there a universal grammar that underlies every actual grammar?

These questions have been asked many times before. My answers are as follows:

  • They come from below, not above.
  • They do have a readily describable structure.
  • That structure does indeed underly every actual grammar.

The first answer is the most important one. If the language of thought precedes symbolic language, then symbolic language is emergent from it, and the way to study is not through self-examination but rather by observing the behavior of non-language speaking agents. Of these my favorite two are babies and dogs. Both exhibit a myriad of strategic behaviors that imply thought but clearly do not entail language. So, based on observing them, what can we say about the structure of such thinking?

Babies and dogs, I propose, process the following five concepts routinely and effectively:

  1. Agents. They recognize and respond to people and animals that can interact with them, as indicated by their eye contact, their coming and going, and response to commands and gestures.
  2. Objects. They recognize and can discriminate among objects that interest them, both inanimate and animate, including foods, toys, playmates, and parents. They do not distinguish between animate and inanimate objects in any consistent way.
  3. Actions. They initiate and respond to actions in ways that further their interests, be that in feeding, playing, or getting attention. They are inherently attracted to action in any form.
  4. Valence. They discriminate between things they like and things they don’t like, seeking the former and avoiding the latter, as witnessed by their eating and their expressions of mood.
  5. Uncertainty. When uncertain, they hesitate and respond tentatively until they can resolve their uncertainty.

My claim is that these five concepts map directly to the fundamental syntax of every one of the six thousand or so symbolic languages currently in use. Agents and objects both convert to nouns and noun-like entities that serve as subjects and predicate objects in declarative statements. Similarly, actions convert to verbs and verb-like phrases. When we combine nouns with actions, we get predications, or what I like to term claims, which are the fundamental units of symbolic discourse. Valences foreshadow the use of adjectives, adverbs, and other modifiers that add nuances to our claims, and uncertainty is represented by modal verbs expressing possibility, probability, or necessity.

As much ground as all this covers, it is important to understand what the language of thought does not entail. Take the sentence “John is tall.” That thought would never occur to either a baby or a dog. It is inherently symbolic in nature, and until you have a symbolic language, it cannot exist. In The Infinite Staircase, it belongs to the stairstep of analytics, whereas the language of thought can reach no higher than the stairstep of narrative.

It is on the stairstep of narrative that the language of thought passes the baton to symbolic language. We cannot tell stories without symbolic language, but it is clear from the behavior of both toddlers and long-term pets that we want to. The connection that binds the two at this point is a realization of cause and effect. Narrative is how we process cause and effect. The breakthrough of symbolic language is that we can not only be a lot more precise in our communication, increasing its efficacy, but also that we can abstract from one narrative concepts and patterns that can be applied elsewhere. This is the miracle of analytics, and it only comes with symbolic language.

To close, let’s revisit our first question—where exactly do our (symbolic-language-expressed) thoughts originate from? This is not a brain-processing question—that landscape is still under investigation—but rather a question of lived experience. Where does it feel like they come from?

My answer is that they are chemically generated responses that represent fluctuations in our homeostatic balance. Like all organisms, we are compelled to seek this balance all the time. The more we get out of balance, the stronger the chemical signal to respond, the more intense the resultant stream of thoughts will be. This applies to dreams as well as to when we are awake. We are continually processing a stream of thoughts that emerge into consciousness and finding their linguistic expression as they do. We register these thoughts through listening to ourselves and shape them further through talking to ourselves. It is only when we get to the talking that we are fully immersed in symbolic language.

That’s what I think. What do you think?

— Image credit: Pixabay

Subscribe to Human-Centered Change & Innovation WeeklySign up here to join 17,000+ leaders getting Human-Centered Change & Innovation Weekly delivered to their inbox every week.
AI ROI and Market Valuations

AI ROI and Market Valuations

GUEST POST from Geoffrey Moore

A recent CNN Nightcap lamented the lack of ROI given the massive investments to date in AI, fueled by equally massive market valuations. This is true but misleading. ROI is a metric that tracks success in the Performance Zone. The big AI players are all playing a game in the Transformation Zone. Investors need to understand the difference and manage their expectations accordingly.

Back in the late ‘90s, Paul Johnson, Tom Kippola, and I published The Gorilla Game, a guide to investing in technology booms. The core concept was Paul’s: investors value companies based on their expectations of future earnings, and they base those in turn on two factors: the Competitive Advantage Gap (GAP) that separates the company’s offerings from their competition, and the Competitive Advantage Period (CAP) that represents the length of time they can sustain that GAP.

In established markets, GAP and CAP oscillate with product release cycles, and over time the industry consolidates around company power as measured by market share. Ecosystems organize around market-share leaders, and customers follow ecosystem leaders, all of which make for a remarkably stable pecking order. Risk-adjusted returns are modest but reliable, and ROI is indeed the right measure for success and is reflected in market valuations by the P/E ratio.

In technologically disrupted markets, a different dynamic is at work. Category power is obsoleting company power, displacing the current ecosystem, calling into question the traditional valuations of current market leaders, and giving rise to very untraditional valuations for next-generation challengers. Whereas the GAP and CAP in traditional markets are modest but stable, say single-digit advantages in GAP with three-to-five-year lengths for CAP, the GAP of a disruptive technology is extraordinary, triple-digits and beyond, and the length of GAP is based on the life of the category itself, typically multiple decades. Risk-adjusted returns are enormous despite the deep J-curve that must be passed through to get to them, something partially captured by a “Rule of 40” metric that combines current revenue growth with current gross margins and ignores profits and cash flows for the foreseeable future.

The CNN nightcap quite reasonably categorized these investments as suitable for venture capital, not for public markets, but a funny thing is happening to capital accumulation as the global economy becomes more and more digital. Whereas the industrial economy is capital-constrained, needing constant investment in factories, inventory, logistics, and distribution to keep it running smoothly, the digital economy is much less so. Yes, it needs factories — aka data centers — but it has no inventory, and it has multiple “asset light” plays when it comes to logistics and distribution. As a result, because management is still incented to maximum returns, capital has been accumulating in massive pools, especially in the coffers of the digital market leaders. This is what allows Microsoft, Google, Meta, Tesla, Amazon, and their ilk to make eye-popping investments in technologies that have yet to deliver meaningful ROI.

Should their shareholders be concerned? Are they managing for shareholder value? Not for short-term value investors, that’s for sure, but for long-term growth investors, the answer is perhaps. It depends on whether the category really does take off, what we call going inside the tornado, and whether their company can win enough market share and generate a sufficiently competitive ecosystem to ride the wave through to the end. It is not an easy bet to make, but the fates of iconic companies like Kodak, Nokia, and AT&T, as well as the current challenges facing the equally iconic Intel, show that not making the bet is not a safe path either.

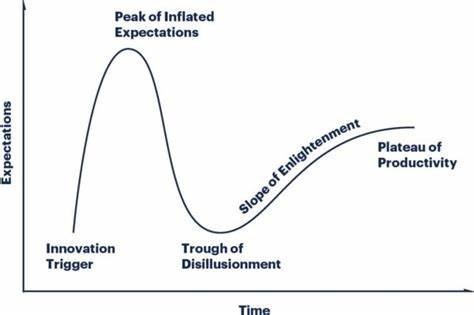
There is one last wrinkle to mention, and that is the impact of what the Gartner Group has called the Hype Cycle.

Gartner Hype Cycle

This model looks very similar to the Technology Adoption Life Cycle, but ironically it is time-shifted such that at the Peak of Inflated Expectations, which is an Early Market phenomenon, many become convinced that the category is instead inside the tornado and commit to massive investments just as they are about to hit the chasm. So, note to all you visionaries: When you get a vision of the future, which you are very good at doing, please look for a calendar to find out what year it is.

That’s what I think. What do you think?

— Image credit: Gemini

Subscribe to Human-Centered Change & Innovation WeeklySign up here to join 17,000+ leaders getting Human-Centered Change & Innovation Weekly delivered to their inbox every week.
Compelling Narratives

Compelling Narratives

GUEST POST from Geoffrey Moore

As human beings we cling to two misconceptions of life. The first is that life is fragile. That is not quite right. Living things are certainly fragile — we are all subject to injury and will eventually die. Even whole species can go extinct. But life itself is anything but fragile. It originated some 3.5 billion years ago and has subsequently taken over the entire planet — land, water, sky, even deep within the earth — and shows no signs of loosening its grip. Life per se, in other words, may be the most powerful force we can experience.

Our second misconception is that, when it comes to our own lives, we are the ones in charge. There is some truth in this, but there is also truth in the notion that life is in charge of us. That is, life per se has an agenda that is independent of us, an agenda in which we are inexorably embedded, one that is grounded in the two universal functions that have enabled it to withstand the test of time — metabolism and reproduction.

We know a lot about these two functions from our study of the microbiology of the cell. Both entail a mindboggling number of chemical reactions chained together by a myriad of cascading pathways that are in turn governed by a byzantine array of positive and negative feedback loops. What is truly astounding is that, working in tandem, they have, from their very inception, been both dynamic — ever-changing—and persistent — continuity-maintaining. Life per se, in other words, is characterized by sustained dynamic equilibrium.

To be sure, life has evolved enormously since its cellular inception. After about 2 billion years of single-celled organisms only, cells began to collaborate with one another, leading to the emergence of additional layers of complexity. Over the 1.5 billion years since, they have generated all the variety of living things we see today, as well as a huge variety of species that have passed out of existence. But amidst all that change, over that entire immensity of time, at the level of the cell itself, this absurdly complex concatenation of cascading processes has never ever stopped. Based on this history, I think we must conclude that living things are compelled to live, and that includes us.

Yes, we can end our lives through suicidal interventions, but we cannot will our hearts to stop beating or our lungs to stop breathing. We can’t stop sleeping, and we can’t stop waking up. In short, we are embedded in something that is much larger and more powerful than our conscious selves, and we need to appreciate how this shapes our lived experience.

It turns out there is a whole tradition in philosophy called phenomenology that takes this premise as its starting point. It is organized around the work of Edmund Husserl and Martin Heidegger, but not in a way I am happy with. Like most philosophers, Husserl and Heidegger anchor their work in analytics and then search for narratives to illustrate their concepts. This runs counter to the fundamental premise of The Infinite Staircase, namely that the stairstep of Narrative precedes the stairstep of Analytics, both in evolutionary time and in order of priority when establishing meaning. That is, you need to get your narratives in focus first and then apply analytics to them, not the other way around.

The reason this is so important is that lived experience expresses itself in narratives, not analytics. Analytics abstract from narratives underlying principles which can be used to refine our strategy for living. This is an incredibly important function, one that underlies virtually all the amelioration of the human condition that we have accomplished over the past several centuries. But analytics cannot substitute for narratives. They cannot capture the immediacy of experience nor engage our sensibility with anything like the power of narratives. We are story-telling creatures, first and foremost. That’s how and where we develop our understanding of cause and effect.

Now, if we take the notion that we are compelled to live and we add it to the notion that narrative is our primary mode for processing lived experience, we can reasonably surmise that we are compelled to tell stories. What might that mean?

Well, for those of us in business, this is not a big surprise. We spend the bulk of our time engaged in storytelling and listening. What are you working on? How is it going? What’s the plan? How did the call go? Did you find that bug? What did Harry want? You get the idea. Stories are our lived experience, even more so if we are working remotely.

More formal occasions call for more formal storytelling, be that a proposal, a report, an analysis, an earnings call, or an annual plan. The point is, in all those situations, we are compelled to tell a story. Now, to be sure, our story may well be challenged–that is the function of analytics—but it is not OK not to tell one. The reason is that all our future actions will ultimately be grounded in a story that we agree to accept. Even the most routine bureaucratic approval cycles involve storytelling at some point in the process. We cannot act without a storyline to guide us. Thus, we are compelled to tell stories.

This is even more the case in the realm of politics. Today we are awash in political storytelling, much of which is being labeled misinformation. But the term is misleading. It implies that the teller has got their facts wrong. But that is not what is happening. Instead, they are telling a story that they believe will generate the political response they are seeking, be that to get themselves elected, or to prevent someone else from being elected, or to get legislation passed, or to block legislation from being passed. Our job as responsible citizens is to apply our analytics to their narratives to detect the ones we endorse and those we repudiate.

In both business and politics, pressure-testing the narratives we are presented with requires both judgment and experience. We normally do not have access to an irrefutable body of facts. Instead, we have to assess the character of the storyteller based on how they come across to us, how self-serving their story might be, how plausible it is, and the like, and we often draw on the opinions of professional commentators whom we have found to be trustworthy. There is no guarantee we are going to get things right, but the more due diligence we do, the more likely we will get close.

But what about all the lies? What about all the blatant liars that are just getting away with it? Why aren’t they being held to account? Why do their supporters believe them? The answer, in my view, is because they want to. People are not stupid. They know when other people are lying. The reason they accede to such lies and bully each other into accepting them is because the story being told validates their lived experience. You or I might repudiate the narrative, but we cannot repudiate their lived experience. That is theirs, not ours.

What we can do is share lived experiences with each other with the goal of finding common values. This requires a level of civility that we see openly mocked and that mockery is perhaps the most dangerous current in our present circumstances. It is not the narratives that are the problem. It is the sneering. We can work our way out of the toughest situations if we respect each other’s perspectives. We cannot do so when we demean or demonize our opponents. Stories and storytelling are the currency of our being. We cannot let it be debased.

That’s what I think. What do you think?

— Image credit: 1 of 1,500+ FREE quotes available at http://misterinnovation.com

Subscribe to Human-Centered Change & Innovation WeeklySign up here to join 17,000+ leaders getting Human-Centered Change & Innovation Weekly delivered to their inbox every week.
The Slowing EV Market

The Slowing EV Market

GUEST POST from Geoffrey Moore

One initiative that is top-of-mind for curtailing climate change is the electrification of ground transportation. The meteoric rise of Tesla drew the world’s attention to EVs, and China’s fast-follower public-private partnership has taken the industry to a whole new level. But now it is encountering a lull, and that raises the question, where do we go from here?

A couple of years ago LG announced a breakthrough in a battery-manufacturing technology called dry-coating that is expected to lower cost from 17 to 30%, with expected deployment in 2028. In a steady-state market, this would be welcome news indeed, but for a market that is still developing, it is not the sort of risk-adjusted return on investment (ROI) nor the kind of rate of return (IRR) that will attract private equity. LG is looking to future growth in its existing battery business to reward its efforts and counting on its investors to have the patience to wait for it.

Meanwhile, in the US, the first wave of venture returns has come and gone, and the next wave depends upon enormous amounts of capital being invested in very long-term charging infrastructure projects, the kind that are normally funded by bonds. This is reminiscent of the national commitment that underwrote the interstate highway buildout in the 20th century, but it is not clear we have the political consensus to prioritize such a project.

Ironically, we do not lack for capital to fund these efforts. The past several decades of digital transformation have created enormous pools of wealth, and financial managers are anxious to put that capital to work. The problem is that, for this phase of investment, the ROI and IRR performance metrics that accompany the creation of that wealth are neither appropriate nor available.

Private capital, for better or for worse, is driven by its compensation systems. We saw this when we tried to leverage its expertise to create carbon-credits exchanges. Not surprisingly that led to a sustained gaming of the system that has generated plenty of fees but done nothing to improve the climate situation. What we need instead is a private-public partnership based on a genuine commitment to global good.

Such a partnership is possible, but only if our political leaders are committed to such values, something we should all keep in mind when we vote this fall. At present, the electoral conversation is so consumed with personalities seeking to score points with abusive rhetoric that there is little prospect for any such partnership to emerge. But we need not capitulate to that rhetoric. If the time to change course is now, then we should hold ourselves and our country accountable for doing so.

That’s what I think. What do you think?

— Image credit: Pexels

Subscribe to Human-Centered Change & Innovation WeeklySign up here to join 17,000+ leaders getting Human-Centered Change & Innovation Weekly delivered to their inbox every week.
The Actual Future of AI

The Actual Future of AI

GUEST POST from Geoffrey Moore

AI is the number one topic in the boardroom this year, and everybody wants to know how it is going to play out and what that means for their enterprise. Well, it’s not as if we have never seen versions of this movie before. How did the Internet play out? The Worldwide Web? eCommerce? Cloud computing? Smartphones? Digital marketing? Ride-sharing? Streaming media?

This is the Technology Adoption Life Cycle at work, for sure, and has been the basis of my life’s work and that of many colleagues as well. That said, however, most of our time has been spent helping clients see how best to navigate the current state of that life cycle, either as a disruptor or a disruptee. That’s all well and good, but what the board really wants to know is what can we expect from the end state. Where will all this land, and what future do we need to prepare for?

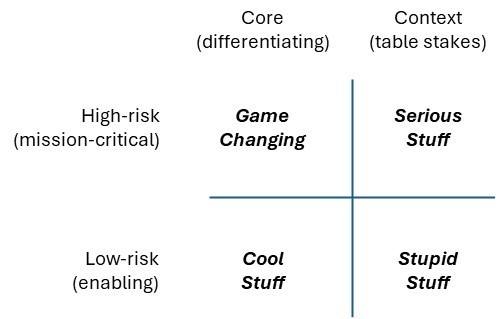
To answer this question properly we need to lay out the landscape of work along two axes (shockingly, creating a 2X2 matrix, the gold standard for all consulting models). One axis discriminates between output that is differentiating, giving customers a reason to choose your offers over those of your competitors, in contrast to work that is industry standard, things every competitor is expected to deliver. The other axis discriminates on the basis of risk exposure, distinguishing between outcomes that are mission-critical where failure is not an option, in contrast to outcomes that can tolerate a certain amount of scrap or rework.

We call this the core/context framework, and when overlaid onto the future of AI, it can look something like this:

Core Context Framework Geoffrey Moore

In the context of this diagram here is how I predict the next ten years of AI will play out:

1. Stupid stuff first. One thing to which we will all testify is that there is no lack of stupid stuff encumbering the workflow of our daily lives. Wherever bureaucracy reigns, there will be an unending stream of compliance requirements, be that in the public or the private sector, and we suffer this burden because it does underpin the rule of law, albeit onerously.

Fulfilling these requirements does not take creative genius, it takes attention to detail and considerable patience. Humans are not strong on either front, but AI is, and this is where enterprises are already weighing in and will continue to do so for the rest of the decade and more.

That said, the ROI from such efforts is modest. Basically, we are automating an inefficient system, which does reduce cost, and does free up human talent to be used elsewhere. But what we find is that human talent is not as fungible as we would want, many displaced workers cannot find employment at a comparable salary, and the rest of the enterprise is not improved in any marked way. Things overall are better, but not a lot better.

2. Cool stuff in parallel. When it comes to new technology, wherever the risk barrier is low, technology enthusiasts will lean in regardless, whether that be on their own time or their employer’s. What they are doing is playing with an inefficient system, seeing what the bright new shiny object might bring to the table. This does take creative genius as well as some creative license, so once again, patience is required, but this time it is on the part of the investor or supervisor.

That said, in the domain of consumer products and services, there is the potential for blockbuster ROI here, as any number of freemium plays have demonstrated in the past. Many are short-lived, to be sure (remember ringtones?), but in their short life, they can capture an extraordinary amount of discretionary spend. And others can mature into abiding infrastructure as search, messaging, and file sharing have all demonstrated.

The key here is that these are not mission-critical and, therefore, do not attract regulatory regimes. If and when they should do so, as is happening with social media now, then their economics can turn upside down in a hurry.

3. Serious stuff takes time. This is where most of the big and abiding ROI will come from. When work is mission-critical but not differentiating, it requires considerable investment in table-stakes processes, which garner no premium in the marketplace. To be brutally honest, there is no prize for doing this work well but considerable penalties for any mistakes you make (think ransomware for a bone-chilling example).

In the 1990s, there was an Internet-enabled revolution in enterprise manufacturing that introduced global outsourcing as a high-ROI way to address mission-critical context workloads—move the work from your company, where it is context, to their company, where it is core. This was a hugely disruptive innovation, allowing the economies of China, India, and now Southeast Asia, to expand at exponential rates, creating increasingly vibrant middle classes where there were none before. However, these benefits have come with a price, both in terms of geopolitical risks, supply chain vulnerabilities, and societal downsides, all of which we are still trying to come to terms with.

Here, AI can have a major impact, not by automating an efficient system, but by completely reengineering it. This will entail on-shoring a lot of manufacturing and displacing a lot of call centers as we introduce more and more AI into these mission-critical workflows. The gains will be in faster response to changing market demands, better returns from high-variability small-volume manufacturing runs, and reduced scrap and rework. At the outset, these changes will entail a considerable amount of human-in-the-loop processing, but eventually, because AI-enabled systems need never stop learning, the human will become the biggest source of error in the system, and we will transition to full autonomy (self-driving cars will be a case study of this transition).

4. Game-changing happens when it happens. There is a reason why so many billionaires have appeared in my lifetime (I personally forgot to become one). Their fortunes are the natural outcome whenever a disruptive innovation does not simply reengineer the existing inefficient system but instead completely replaces it. Amazon Prime, Uber, Netflix, Salesforce, NVIDIA, Apple — each company categorically changed the landscape, rendering the incumbents irrelevant, redirecting the cash flows of their entire industry to flow past their doors.

These outcomes are inevitable, but they are also unpredictable. They are what puts the venture in venture capital. The good news for incumbents is that they do not happen very often, and even when they appear to be succeeding, they can still stumble and fall. That said, sooner or later there will be a reckoning, and that is when the incumbents need to activate their Transformation Zone if they are going to survive the transition.

My altruistic wish is that for AI, this time around, the target will be the public sector. Higher education, social services, healthcare, and law enforcement are all staggering under increasingly untenable demands accompanied by shrinking workforces and restricted budgets. All of them are target-rich environments for applying AI both to stupid stuff and serious stuff. We have never disrupted these sanctums in the past, each having been ruled by regulatory regimes and professional guilds that have deeply conservative roots blocking the kinds of changes that are now needed. Displacing these systems will take decades, but the ROI, both financial and social, would be truly game-changing.

That’s what I think. What do you think?

— Image credit: Gemini

Subscribe to Human-Centered Change & Innovation WeeklySign up here to join 17,000+ leaders getting Human-Centered Change & Innovation Weekly delivered to their inbox every week.
Is Your AI in the Zone to Win?

Whether you are catching up, keeping up, getting ahead, and fending off an existential threat, get in the zone!

Is Your AI in the Zone to Win?

GUEST POST from Geoffrey Moore

We’re already almost three years into the modern AI era, and everyone wants to know — What are we doing with AI? The board wants to know, the sales team wants to know, the customers want to know, the analysts want to know. Heck, you want to know.

So, how do you decide?

Start with a clear-eyed assessment of where your company stands relative to its peers in your industry. Are you behind? Are you on par but need to keep up? Are you out ahead or have a chance to be so? Or, in a darker vein, is AI opening your entire industry up to disruption, putting you and your peers under existential threat? The good news is that there are playbooks for dealing with each of these situations. The caveat is that they are all different. You need to execute them, if not linearly, then at least separately. And that’s where zone management can be a big help.

Catching Up

Industries in catch-up mode with respect to implementing AI might include retail (supply chain management, contact center productivity), higher education (admissions, alumni relations), and public sector (regulatory compliance services). The wolf is not at the door, but with AI moving as fast as it is, time is not your friend, so you need to get cracking. This is a job for the Productivity Zone.

Every organization in this zone — finance, HR, marketing, purchasing, customer success, security, you name it—is a candidate for implementing some kind of AI on a low-risk, get-acquainted basis. None of these applications will be so dramatic as to disrupt normal services, but each will give your AI team hands-on experience with the latest available technology, and most should deliver enough ROI to pay for themselves. Even when they don’t, they will contribute to the “Win or Learn” kitty, and that is what catching up is all about.

The key here is to move fast and on every front. That means every organization in this zone has to participate every quarter. Conduct AI progress reviews to hold each org leader accountable for net new wins or learnings every quarter. The goal is to catch up within a year, and it is important enough to tie performance to discretionary compensation to ensure both prioritization and inspection.

Keeping Up

Industries in a keep-up model with respect to implementing AI might include insurance (underwriting, claims), management consulting (tax, audit), and public sector (tax collection). All these areas represent customer-facing processes that are currently served by humans loaded down with routine work that can be done better, faster, and cheaper by AI applications. This is a job for the Performance Zone.

The goal here is to use AI to increase the competitiveness of your established lines of business, either through materially differentiating your products or dramatically reengineering your processes to lower costs, speed response times, and improve quality. The current generation of AI technology, because it is so remarkably approachable, is ready-made to take on this work. Your job is to make sure you use it to target those opportunities where there is the most trapped value to release. These will likely be a bit more gnarly than the others, but when you are mining for gold, you have to go where the gold is.

Generating such higher returns does not come without taking risk. Good as it is, AI is still a work in progress, so you will likely be taking a human-in-the-loop approach for the foreseeable future. The good news is your workforce is expert in your business, so you have the guard rails you need already in place. The challenge is that we humans are comfortable in our established routines, and you need everyone to break out of the old ways to free your company’s future from the pull of the past. This is more of a change management problem than an AI issue, so you should have no qualms about holding the leaders of this zone accountable.

Getting Ahead

Industries with a lot of built-in trapped value represent opportunities for first-movers to get ahead of their peers by radically reengineering the way business gets done. Examples might include residential real estate (title insurance, buyer agent compensation), health care (value-based care, home care), and public sector (social services). In each case, traditional bureaucracies are at odds with where the industry needs to go next, and implementing AI applications can be highly disruptive. This is a job for the Incubation Zone.

Venture-backed start-ups are normally the fastest movers here, but they take a long time to scale. Established enterprises have the customers, the ecosystems, and the balance sheets to get to the finish line first if they can get out of their own way. That’s what the Incubation Zone is designed to do. As described at length in Zone to Win, it emulates the VC operating model without attempting to replicate its financial model. The goal is to win early market marquee customers and cross the chasm, all without any help (or hindrance) from the core business. You have all the resources you need to do this, but it requires muscles you haven’t used in a long time, so funneling one or more acquisitions into the Incubation Zone is often a good tactic.

The key challenge will come when you reach enough scale to bring the new line of business into the Performance Zone. In the best of circumstances, you can leverage the more forward-thinking elements in your partner ecosystem and customer base to create a soft landing, running both the old and new lines side by side, as Netflix did for some time with its DVD and streaming businesses. Sooner or later, however, you will have to rip off the Band-Aid and make the transition to the new path, again as Netflix did.

Fending Off an Existential Threat

At present, the existential threat posed by Generative AI and its successors is still hard to predict, but two industries that have already sensed it are media entertainment (content creation, acting) and publishing (copyright, fair use). What should their playbook be?

This is a job for the Transformation Zone. The playbook requires all four zones to fly in formation to get through a very rough patch. The Productivity Zone goes into action first, launching legal actions against the invaders and pursuing lobbying efforts to get protective legislation. This is not a long-term solution, but it does buy some much needed time.

Meanwhile, the Incubation Zone is charged with catching up to the new wave as fast as possible. The goal here is not to out-innovate the innovators. That is what Yahoo tried to do to fend off Google, and Nokia to fend off Apple. The attackers are too good at what they do, and you are playing their game. Instead, take a lesson from how Microsoft has played catch-up throughout its storied history, beginning catching WordPerfect with Word, Lotus 123 with Excel, Aldus Persuasion with PowerPoint, and moving on to the Mac GUI with Windows, Novell with Windows NT, and Netscape Navigator with Internet Explorer. Most recently, they executed the catch-up-fast playbook to head off Amazon Web Services with Azure. The key to their success is to get to “good enough, fast enough,” not to out-perform the disruptor but to keep their own existing customer base on their side, again buying time to innovate further once it is clear they are in the game to stay.

One thing you do not want to do as an established enterprise is to merge with a successful disruptor. The Time Warner AOL merger provides a cautionary lesson here. The cultures are too different, and the necessary level of mutual trust just isn’t there, so instead of running in parallel, they work at cross purposes, and the result is a tangled mess.

On the Performance Zone side, you have to keep pedaling (and peddling) the legacy line of businesses. Absent private equity, they are your only source of capital, and they are still providing value. But you have to realize that their profit margins are under direct attack and can only be defended through rear-guard actions. That is, your legacy profit pool is the current site of trapped value, and draining it is what is funding the next wave of innovation. You don’t like it, and your investors hate it, but that’s the hand you have to play.

And that brings us to the Transformation Zone proper. You are going through a transition, the intermediate stages of which are ugly, making everyone cranky, and causing rampant second-guessing of every move you make. This is where the CEO must lead with clarity, transparency, and conviction, rallying the troops, reaching out to the customer base, providing an investable narrative to the stakeholders, and reassuring the partner ecosystem. Moreover, every senior executive must unequivocally support the chosen path or else be asked to leave. When you are under existential threat, there can be no fooling around.

Summing Up

The AI tsunami is upon us, and we can expect wave after wave of disruption for the rest of this decade and the next one as well. Clearly, it offers a wealth of opportunity, but as with all waves, catching it depends on getting your timing right and finding the right angle of attack. The four playbooks outlined above have been tested over many decades within the high sector as it dealt with the disruptive impact of the microprocessor, the Internet, cloud computing, SaaS applications, smartphones, and social media. You may not be as familiar with them as you would like, but the risk of waiting on the sidelines exceeds the risk of taking the plunge, so I can only encourage you to grab your nose plugs and jump in.

That’s what I think. What do you think?

— Image credit: Gemini

Subscribe to Human-Centered Change & Innovation WeeklySign up here to join 17,000+ leaders getting Human-Centered Change & Innovation Weekly delivered to their inbox every week.